
Dealer Gamma Vanna Charm Flows
Single-Stock Call-Skew Inversion & Dealer Short-Call Gamma Squeezes
Dissect the anatomy of single-stock upside gamma squeezes: how aggressive OTM call buying in high-short-interest equities inverts 25-delta skew, turns spot-vol correlation positive (ρ > +0.60), and forces simultaneous Gamma + Vanna dealer share buying.
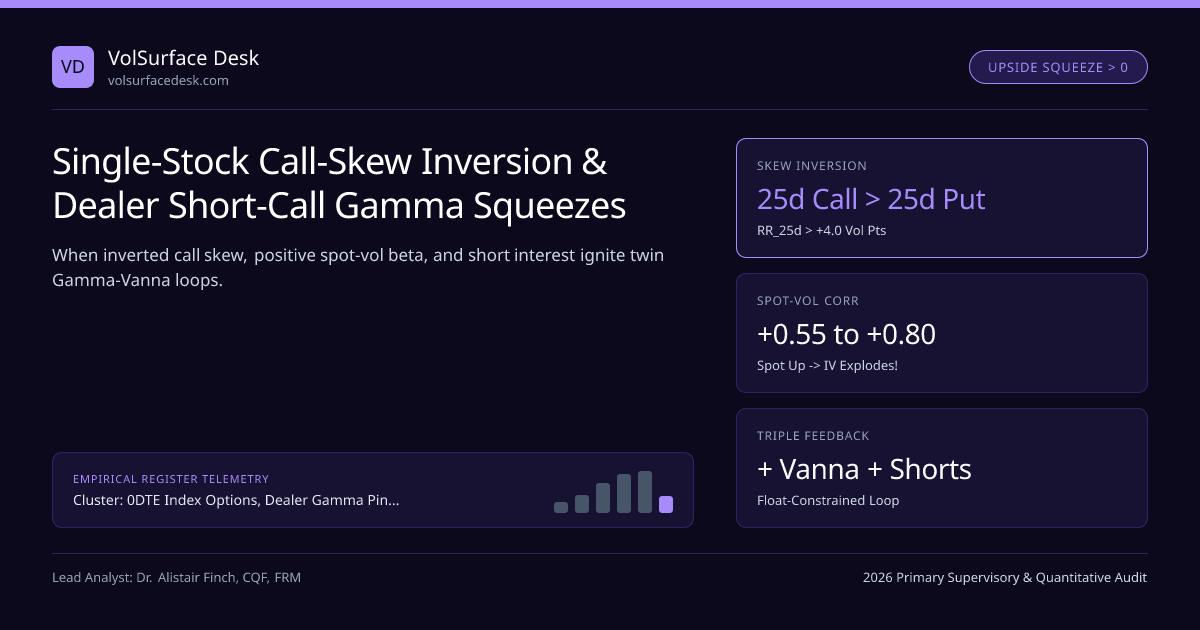
Broad equity indices like the S&P 500 exhibit negative spot-volatility correlation (ρ ≈ −0.75): rallies calm implied volatility while selloffs spike fear. Single-stock equities with constrained public float and elevated short interest (>15%–25% of float) can flip that physics completely upside down! When coordinated or momentum-driven buyers sweep weekly out-of-the-money call options, the volatility surface undergoes call-skew inversion—turning market makers and short sellers into reluctant buyers in a self-reinforcing Gamma + Vanna + Short-Cover feedback loop.
Within the 0DTE Index Options, Dealer Gamma Pinning, Vanna & Charm Rehedging silo and our 0DTE Dealer Gamma, Vanna & Charm Flows Guide, analyzing this positive-ρ instability is vital for both equity long/short risk managers and single-name dispersion desks.
Twin-Accelerator Math: Why Positive Spot-Vol Beta Doubles Dealer Share Buying#
Examine the sign of Black-Scholes Vanna on an out-of-the-money Call where strike K sits substantially above forward F (ln(F/K) < 0 so d2 < 0):
- Because Vanna = −e^(−qT) · φ(d1) · (d2 / σ) and d2 < 0, OTM Call Vanna is strictly POSITIVE (∂Δ_call / ∂σ > 0)!
- Intuitively, at 40% IV a 30%-OTM weekly call has almost zero chance of finishing ITM (Δcall = +0.06); if call IV explodes to 160% IV during a frenzy, that exact same strike leaps to Δcall = +0.34 even BEFORE spot moves!
Now combine short-call Gamma (ΔS > 0), short-call Vanna (Δσ > 0), and physical short-seller borrow recalls (Qshortcover > 0) against a limited free float Float_sh:
Quantitative Pricing Model: Single-Stock Call-Skew Inversion & Gamma Squeezes Guide#
- Float Absorption Ratio (FAR): [ Nshortcalls × 100 × Δcall + ShortInterestshares ] / FreeFloat_shares.
- Call-Skew Inversion Trigger: Risk Reversal RR_25d = σ(25d Call) − σ(25d Put) crosses > +4.0 vol points!
- Worked High-Short-Interest Squeeze (Stock S0 = $40.00, Free Float = 45M sh, Short Interest = 11M sh [24.4%], Customers Buy 250,000 5-DTE $55 Calls):
- Initially σ = 65% => Δcall = +0.11 (Dealers hold 2.75M sh). Stock jumps to $48 (+20%) AND σ explodes to 145% => Δcall surges to +0.46! Dealers must buy +8.75M MORE shares (19.4% of entire float!) in hours!
Equity risk managers stress-test OTM call delta explosions under joint spot-plus-IV jumps in our Black-Scholes Option Calculator and Option Greeks & GEX Calculator.
The Triple-Feedback Single-Stock Upside Squeeze Loop#
Index Skew vs Single-Stock Squeeze Skew Comparison#
| Volatility Surface Metric | Normal S&P 500 Index Surface | Pre-Squeeze Single Stock (Warning) | Active Upside Gamma Squeeze |
|---|---|---|---|
| 25d Call − 25d Put (RR_25d) | −4.5 to −7.5 vol pts (Put skew) | +2.5 to +6.0 vol pts (Inverted!) | +15 to +45+ vol pts (Extreme right wing) |
| Spot-Vol Correlation (ρ) | Strongly Negative (−0.70 to −0.82) | Crossing Positive (+0.25 to +0.45) | Strongly Positive (+0.60 to +0.85) |
| 10-Delta Butterfly (BF_10d) | Moderate (+2.2 to +3.8 vol pts) | Expanding rapidly (+6.5+ vol pts) | Extreme Vomma convexity (+25v+) |
| Prime Broker Margin (Rule 4210) | Standard −8% / +6% TIMS | House stress raised to ±35% | 100%–300% concentrated short-call margin! |
Decomposition of Dealer Share Hedging in an Upside Call Squeeze#
As documented in the SEC Staff Report on Equity and Options Market Structure and enforced via OCC STANS single-name concentration add-ons, institutional equity short-sellers never carry uncovered single-stock shorts when RR_25d > +4.0v without capping upside loss via call spreads.
Frequently asked questions
Why do Gamma and Vanna reinforce each other during an upside call squeeze instead of offsetting?
For an OTM call (d2 < 0 when K > F? Careful: for K >> F, ln(F/K) < 0 so d2 < 0 => Vanna = -φ(d1)·d2/σ > 0!). Raising implied volatility INCREASES an OTM call’s delta from +0.12 toward +0.35! When dealers are short OTM calls and BOTH spot rises (+Gamma) AND IV rises (+Vanna), dealers must buy shares from both effects simultaneously!
What early volatility-surface signal warns short sellers of an impending gamma squeeze?
Watch the 7-to-30 DTE 25-delta Call-minus-Put Risk Reversal (RR_25d = σ_25C − σ_25P) alongside Cboe/OPRA Customer Buy-to-Open call volume as a percentage of free-float shares. When RR_25d crosses from negative (-3v) to >+4.0 vol points while short interest exceeds 18% of float, squeeze convexity is armed.
How do market makers price new upside call strikes once a stock blows past the highest listed strike?
Exchanges list emergency expanded strike series overnight, and dealers extrapolate upside variance using positive-ρ SABR/SVI parameters plus massive Leland hedging-cost surcharges (often 120%–300% IV), ensuring option ask prices embed extreme discrete gap risk.
Why do upside single-stock gamma squeezes collapse just as violently once call buying stalls?
Once fresh OTM call buying pauses for even 4 hours, both Charm (rapid weekly OTM call delta decay) and Vanna (falling call IV shrinking call deltas from +0.35 back to +0.12) flip sign simultaneously—turning dealers into mechanical sellers of millions of hedged shares!
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). Single-Stock Call-Skew Inversion & Dealer Short-Call Gamma Squeezes. VolSurface Desk. https://volsurfacedesk.com/desk-notes/single-stock-call-skew-inversion-gamma-squeezesRelated Dealer Gamma Vanna Charm Flows & Institutional Briefings
Explore Dealer Gamma Vanna Charm Flows Hub (20) →Dealer Gamma Vanna Charm Flows
0DTE Index Options, Net Dealer Gamma (GEX), Vanna & Charm Rehedging Flows GuideDealer Gamma Vanna Charm Flows
0DTE Intraday Variance-Time Clock vs Wall-Clock Theta & Event JumpsDealer Gamma Vanna Charm Flows
Net Dealer Gamma Exposure (GEX) Zero-Gamma Flip Points & Volatility RegimesDealer Gamma Vanna Charm Flows
Intraday 0DTE SPX Gamma Scalping vs 15:50 ET NYSE MOC Liquidity CollisionsDealer Gamma Vanna Charm Flows
Vanna (∂Δ/∂σ) Mechanical Equity Rallies After CPI & FOMC Volatility CrushesDealer Gamma Vanna Charm Flows
Charm (∂Δ/∂t) Time-Bleed Mechanics: Intraday, Weekend & OPEX Equity DriftDealer Gamma Vanna Charm Flows
Vomma (Volga, ∂2V/∂σ2) Wing Convexity: Why Short 5-Delta Strangles Blow UpDealer Gamma Vanna Charm Flows
Speed (∂Γ/∂S) Third-Order Gamma Gradients & 0DTE Iron Condor Strike CliffsVix Futures Variance Swap Convexity
CFE & OCC VIX Futures–Options Cross-Margining & Capital OptimizationFX Risk Reversal Strangle Surfaces
FX ATM Delta-Neutral Straddles (DNS) & Premium-Adjusted Delta ConventionsFX Risk Reversal Strangle Surfaces
FX 25-Delta Risk Reversals: USD/JPY & EUR/USD Carry Crash SkewFX Risk Reversal Strangle Surfaces
FX Market Strangle (1-Vol) vs Smiley Broker Butterfly (2-Vol) Iteration
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.