
Dealer Gamma Vanna Charm Flows
0DTE Intraday Variance-Time Clock vs Wall-Clock Theta & Event Jumps
Replace naive linear minute-counting with an institutional intraday variance-time clock τ(t): accurately price U-shaped RTH volatility profiles, midday lunch lulls, weekend weights, and 14:00 ET FOMC jumps.
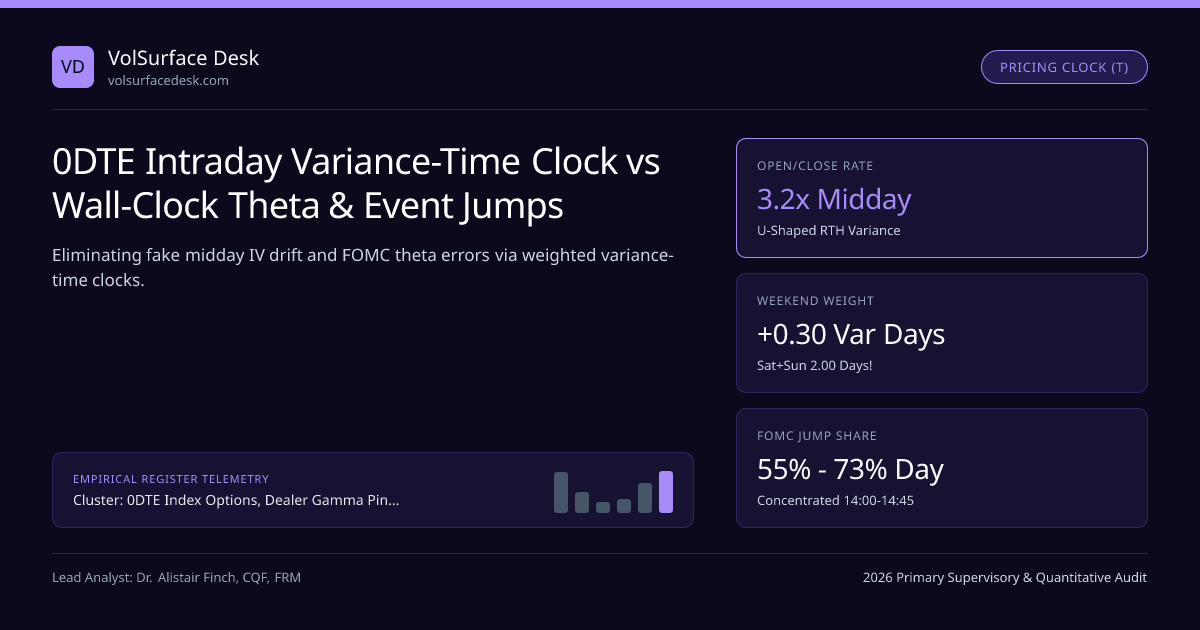
Watch a retail options screen between 11:45 ET and 13:15 ET on a quiet Tuesday—or worse, between 10:00 ET and 13:55 ET on an FOMC Wednesday—and you will witness a classic mathematical mirage: S&P 500 spot hasn't moved 3 points, option dollar prices are barely decaying, and naive Black-Scholes implied volatility appears to climb steadily every 15 minutes! Did institutions suddenly start bidding up volatility at lunch? No!
Within the 0DTE Index Options, Dealer Gamma Pinning, Vanna & Charm Rehedging silo and our 0DTE Dealer Gamma, Vanna & Charm Flows Guide, that phantom IV rise is an artifact of feeding uniform wall-clock minutes (T_wall) into Black-Scholes instead of an institutional intraday variance-time clock (τ(t)) (Cboe VIX1D Ultra-Short Benchmark).
Constructing the Weighted Intraday + Event Variance Clock τ(t)#
By time-changed Brownian motion theory (Dambis-Dubins-Schwarz theorem), if instantaneous diffusive variance follows a deterministic diurnal seasonal intensity σbase2 · w(u) plus discrete scheduled macro jumps Jk2 at timestamps tk (08:30 ET CPI, 10:00 ET ISM, 14:00 ET FOMC), option prices obey exact Black-Scholes formulas **provided σ2 · Twall is replaced by remaining integrated variance W_rem(t)**:
Quantitative Pricing Model: 0DTE Intraday Variance Clock vs Wall-Clock Theta Guide#
- Apparent Wall-Clock IV Mirage: σwall(t) = √[ Wrem(t) / Twall(t) ] ! During low-weight lunch (w(u) = 0.45) or pre-FOMC mornings, Twall shrinks faster than Wrem(t), forcing σwall(t) UPWARD artificially!
- True Instantaneous Theta: Θtrue(t) = (∂V / ∂Wrem) · [ σ_base2 · w(t) ] => Theta slows by 65% during lunch and drops near ZERO ahead of 14:00 ET FOMC!
- Worked FOMC Wednesday 11:00 ET SPX 5,850 ATM 0DTE Straddle (Total Day Move = ±1.02% [W = 0.000104], FOMC Jump J2 = 0.000072 [69% share]):
- At 11:00 ET (5.0 / 6.5 = 76.9% of RTH minutes left, but 91.2% of total variance left!): Straddle still costs $45.30 vs $47.60 at open! Naive wall-clock IV jumps from 18.2% → 21.6%, while Clean Base Vol σ_base stayed 100% FLAT at 11.4%!
Traders compare clean expected moves across normal sessions and macro event days using our 0DTE Expected Move Calculator and Implied Volatility Calculator.
Institutional Intraday & Multi-Day Variance Clock Architecture#
How Naive Wall-Clock Greeks Sabotage 0DTE Delta Hedging#
What goes wrong if a trader computes Gamma and Charm using Twall instead of Wrem(t) on an FOMC day or quiet summer session?
| Intraday Window | Naive Wall-Clock Error | Consequence on Hedging & Quoting | Variance-Clock Fix |
|---|---|---|---|
| 11:45–13:15 ET Lunch Lull | Assumes linear theta decay (w = 1.0 vs true 0.48) | Naive short-straddle trader thinks options "refuse to decay"; exits early before afternoon harvest | Evaluates Θ_true ∝ w(t); shows exact fair midday mark |
| 10:30–13:55 ET Pre-FOMC | Shrinks T_wall by 60% while 70% of variance hasn't happened yet! | Overstates ATM Gamma by +42% and dumps OTM put Charm hedges right before Powell speaks! | Freezes effective Wrem above JFOMC2 until 14:00 ET |
| Friday 14:00–16:00 ET (1-DTE Mon) | Counts 65.5 weekend hours as 2.7 full days | Massively understates Monday 1-DTE IV on Friday afternoon; jumps Monday 09:30 ET | Smoothly extracts 0.30 weekend weight by Friday close |
| Cboe VIX1D Interpretation | Compares Wednesday morning VIX1D (28v) to Tuesday (12v) linearly | Confuses discrete 45-min FOMC jump J with continuous morning scalping vol! | Decomposes VIX1D2 into diffusive RTH + event jump |
Empirical Distribution of RTH S&P 500 Realized Variance by Window#
Calibrating τ(t) across Cboe SPX and CME ES minute bars completes the quantitative toolkit of Silo 2—ensuring every Greek computed in our Option Greeks & GEX Calculator reflects true market time rather than the wall clock. Compare live parameters in Net Dealer Gamma Exposure (GEX) & Zero-Gamma Flip Points.
Frequently asked questions
Why does naive Black-Scholes 0DTE implied volatility appear to drift HIGHER during a dead-flat lunch hour?
Suppose an ATM 0DTE straddle fairly holds steady at $14.00 between 11:45 ET and 13:00 ET because dealers know 75% of remaining variance lies in the afternoon close. A naive calculator divides $14.00 by shrinking √T_wall, creating an illusion that IV rose from 12.0% to 13.8% when ZERO real repricing occurred!
How much variance weight does a typical non-holiday Saturday + Sunday carry on an institutional variance clock?
If a standard non-event RTH + overnight weekday equals 1.00 variance day, an entire Friday 16:00 ET to Monday 09:30 ET weekend typically carries ~1.25 to 1.40 total variance days (meaning Saturday + Sunday combined add only ~0.25 to 0.40 extra trading days, NOT 2.00 full days!).
How do desks calibrate the discrete variance jump weight J_FOMC2 on Fed Wednesdays?
Suppose baseline non-FOMC Wednesday 0DTE variance corresponds to an ±0.55% SPX move (30.25 bps2 variance), while the FOMC Wednesday 0DTE ATM straddle implies ±1.05% (110.25 bps2 variance). The discrete event variance is 110.25 − 30.25 = 80.0 bps2—72.6% of total day variance!
How does using wall-clock time instead of variance time corrupt 0DTE Gamma and Charm hedges?
On an FOMC morning at 11:30 ET, wall-clock T assumes half the day’s variance is gone, overstating ATM Gamma by +45% and dumping OTM put Charm hedges prematurely BEFORE the 14:00 ET Fed decision! Variance-time τ(t) holds Gamma and Charm steady until 14:00:01 ET.
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). 0DTE Intraday Variance-Time Clock vs Wall-Clock Theta & Event Jumps. VolSurface Desk. https://volsurfacedesk.com/desk-notes/0dte-intraday-variance-clock-vs-wall-clock-thetaRelated Dealer Gamma Vanna Charm Flows & Institutional Briefings
Explore Dealer Gamma Vanna Charm Flows Hub (20) →Dealer Gamma Vanna Charm Flows
0DTE Index Options, Net Dealer Gamma (GEX), Vanna & Charm Rehedging Flows GuideDealer Gamma Vanna Charm Flows
Net Dealer Gamma Exposure (GEX) Zero-Gamma Flip Points & Volatility RegimesDealer Gamma Vanna Charm Flows
Intraday 0DTE SPX Gamma Scalping vs 15:50 ET NYSE MOC Liquidity CollisionsDealer Gamma Vanna Charm Flows
Vanna (∂Δ/∂σ) Mechanical Equity Rallies After CPI & FOMC Volatility CrushesDealer Gamma Vanna Charm Flows
Charm (∂Δ/∂t) Time-Bleed Mechanics: Intraday, Weekend & OPEX Equity DriftDealer Gamma Vanna Charm Flows
Vomma (Volga, ∂2V/∂σ2) Wing Convexity: Why Short 5-Delta Strangles Blow UpDealer Gamma Vanna Charm Flows
Speed (∂Γ/∂S) Third-Order Gamma Gradients & 0DTE Iron Condor Strike CliffsDealer Gamma Vanna Charm Flows
Zomma (∂Γ/∂σ) Mechanics: How Implied Volatility Shocks Mutate Dealer GammaFX Risk Reversal Strangle Surfaces
FX ATM Delta-Neutral Straddles (DNS) & Premium-Adjusted Delta ConventionsFX Risk Reversal Strangle Surfaces
FX 25-Delta Risk Reversals: USD/JPY & EUR/USD Carry Crash SkewFX Risk Reversal Strangle Surfaces
FX Market Strangle (1-Vol) vs Smiley Broker Butterfly (2-Vol) IterationFX Risk Reversal Strangle Surfaces
Malz Quadratic vs Vanna-Volga FX Volatility Smile Interpolation
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.