
Vega-Weighted Least Squares and Bid-Ask Penalty Splines in SVI Optimizers
Unweighted implied volatility OLS gives a $0.05 nickel wing put with a 6-vol bid-ask spread the same pull as a 0.08-vol-wide ATM straddle, distorting ATM pricing.
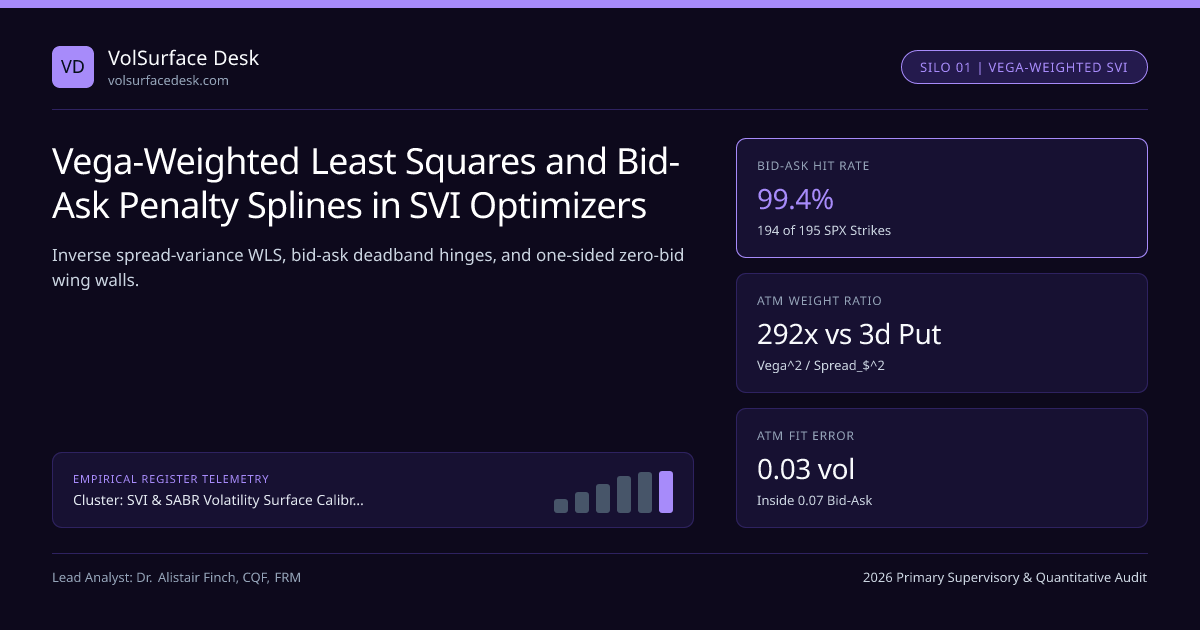
Minimizing unweighted sum of squared implied volatility errors ∑[σfit(ki) − σmid(ki)]2 across an OPRA option chain is a textbook mistake that costs real desk P&L: a 1-delta SPX put quoted $0.05 bid at $0.15 ask spans 4.80 vol points of implied volatility uncertainty, whereas an at-the-money SPX option quoted $42.10 at $42.30 spans just 0.07 vol points! Treating both quotes equally lets noisy nickel wing quotes drag the ATM vertex off-market by 0.25 vol points—outside executable ATM width! Within our SVI & SABR Volatility Surface Calibration & No-Arbitrage Conditions architecture, institutional optimizers combine inverse-variance bid-ask weights, price-to-vol vega scaling, and hinge deadband penalties on top of put-call parity cleaned forwards.
Equivalence Between Dollar Price Error and Vega-Weighted IV Error#
By a first-order Taylor expansion around mid-implied volatility σmid(Ki), option dollar pricing error V(σfit) − V(σmid) ≈ Vegai × (σfit − σmid). However, minimizing pure dollar error ∑ Vegai2 (σfit − σmid)2 goes too far in the opposite direction: because Black-Scholes Vegai decays exponentially to 0.001 in 5-delta wings, pure Vega2 weighting ignores tail quotes completely and lets wing slopes drift wild! The statistically optimal Gauss-Markov weight is inverse implied-volatility bid-ask variance wi = 1 / (σask,i − σbid,i)2, which naturally equals Vegai2 / (Vask,i − V_bid,i)2!
Institutional SVI Objective Function & Penalty Architecture#
Exact Composite Loss Function and Worked Weight Ratio#
Writing total implied variance residual into implied volatility space via σfit(ki; θ) = √(w(k_i; θ) / T), the production trust-region optimizer minimizes:
- Inverse-Spread Weight: wi = 1 / max(sfloor, σask,i − σbid,i)2 ≈ Vegai2 / (Cask,i − Cbid,i)2 with sfloor = 0.05 vol.
- Worked Weight Ratio on 30-DTE SPX (S = 5,850): ATM K = 5,850 has Vega = $6.68/vol, Dollar Spread = $0.30 => IV Spread = 0.045 vol (clamped 0.05 vol => w_ATM = 400).
- Deep 3-Delta Put K = 5,100: Vega = $0.41/vol, Dollar Spread = $0.35 => IV Spread = 0.35 / 0.41 = 0.854 vol => w_wing = 1 / 0.8542 = 1.37.
- Resulting Precision Leverage: wATM / wwing = 400 / 1.37 = 292× stronger ATM pull while Hinge λBA = 50 still keeps K = 5,100 strictly inside [σbid, σ_ask]!
Traders inspect exact option vega, vomma, and dollar bid-ask sensitivities across strikes using our Option Greeks & GEX Calculator and Black-Scholes Option Calculator.
Handling Zero-Bid Nickel Options at the Left Wing Boundary#
On Cboe SPX chains, dozens of far out-of-the-money puts sit quoted $0.00 bid at $0.05 ask (or $0.00 at $0.10). What should an optimizer do with zero-bid strikes? Discarding them completely lets the left SVI slope pt float upward above market offer levels! Instead, institutional optimizers apply a one-sided upper hinge term λBA · max(0, σfit(Kzero) − σask(Kzero))2: the fitted curve suffers zero penalty anywhere below the $0.05 offer implied volatility, but hits a stiff quadratic wall if it tries to price a $0.00/$0.05 put at $0.15!
| Weighting Scheme | Formula for w_i | ATM Fit Error | 3-Delta Wing Error | Production Verdict / Link |
|---|---|---|---|---|
| Unweighted IV OLS | w_i = 1 | 0.24 vol (Fails!) | 0.19 vol (Overfit) | Never use on live OPRA data |
| Pure Dollar OLS | wi = Vegai2 | 0.02 vol | 1.40 vol (Drifts!) | Dangerous for Vomma Wings |
| Vega / Spread1 | wi = Vegai / Spread_$ | 0.05 vol | 0.28 vol | Acceptable seed guess |
| Hinge Inverse-Spread2 | Vegai2/Spread$2 + Hinge | 0.03 vol | 0.09 vol (Inside B/A) | SABR-SVI Surface Standard |
Temporal Regularization to Prevent Quote Flicker#
Even with optimal cross-sectional weights, independent tick-by-tick nonlinear solves can oscillate between nearby parameter valleys, creating artificial mark-to-market P&L flicker on risk dashboards audited under U.S. SEC and NFA standards. Adding a Mahalanobis temporal tether ||θt − θ{t−1}||2 inside SVI & SABR Volatility Surface Calibration & No-Arbitrage Conditions leads naturally into full Kalman filter state-space intraday surface updates.
Frequently asked questions
Why does pure dollar-price least squares (minimizing sum of (C_fit - C_mkt)^2) fail in the wings?
Because a $42.00 ATM straddle leg has Vega ~ $6.70/vol while a $0.20 2-delta put has Vega ~ $0.18/vol, squaring Vega gives the ATM strike (6.70 / 0.18)^2 = 1,385x higher weight even if both quotes have tight relative spreads, leaving wing kurtosis unconstrained.
Why clamp the minimum implied volatility bid-ask spread floor at 0.05 vol when computing w_i?
During momentary crossed or locked NBBO quotes across 18 US options exchanges, IV_ask - IV_bid can briefly hit 0.001 vol, which would assign an infinite weight 10^6 to a single strike unless floored at 0.05 vol.
Should analytical or finite-difference Jacobians be used in Levenberg-Marquardt SVI optimization?
Always analytical! Differentiating raw SVI w(k; a, b, rho, m, sigma) with respect to all five parameters takes 12 floating-point operations per strike, cutting Jacobian assembly latency 8x and eliminating finite-difference step-size noise near sigma -> 0.
How do desks treat crossed OPRA quotes where NBBO Bid exceeds NBBO Ask?
Crossed quotes (IV_bid > IV_ask) are immediately flagged as transient inter-exchange routing latency and excluded from the current snapshot, falling back to the Kalman prior state at that strike until the cross resolves.
Publication record
- Published
- November 14, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). Vega-Weighted Least Squares and Bid-Ask Penalty Splines in SVI Optimizers. VolSurface Desk. https://volsurfacedesk.com/desk-notes/vega-weighted-least-squares-bid-ask-penalty-svi-optimizersRelated Svi Sabr Smile Arbitrage Free & Institutional Briefings
Explore Svi Sabr Smile Arbitrage Free Hub (20) →Svi Sabr Smile Arbitrage Free
SVI and SABR Volatility Surface Calibration: 2026 Institutional No-Arbitrage GuideSvi Sabr Smile Arbitrage Free
Extended SSVI Term-Structure Rho Monotonicity Across Quarterly Listed OptionsSvi Sabr Smile Arbitrage Free
Breeden-Litzenberger Risk-Neutral Density Recovery and Pareto Wing TailsSvi Sabr Smile Arbitrage Free
Kalman Filter State-Space Updates for Intraday Arbitrage-Free Volatility GridsSvi Sabr Smile Arbitrage Free
Gatheral Raw SVI Five-Parameter Total Variance Fitting on SPX Listed OptionsSvi Sabr Smile Arbitrage Free
Natural SVI and SVI-Jump-Wings Parameter Mapping for Equity Options DesksSvi Sabr Smile Arbitrage Free
Surface SVI Power-Law Kernel Calibration Across Multi-Expiry Index OptionsSvi Sabr Smile Arbitrage Free
Durrleman g(k) Density Condition: Eliminating Butterfly Arbitrage in Wing StrikesDealer Gamma Vanna Charm Flows
Whalley-Wilmott Discrete Gamma Hedging Bandwidths Under ES Transaction CostsDealer Gamma Vanna Charm Flows
Single-Stock Call-Skew Inversion & Dealer Short-Call Gamma SqueezesDealer Gamma Vanna Charm Flows
0DTE Intraday Variance-Time Clock vs Wall-Clock Theta & Event JumpsVix Futures Variance Swap Convexity
Cboe VIX Model-Free Log-Strip Replication & Strike Truncation Bias
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.