
FX Risk Reversal Strangle Surfaces
FX ATM Delta-Neutral Straddles (DNS) & Premium-Adjusted Delta Conventions
Avoid the #1 coding bug in FX volatility surfaces: derive exact Garman-Kohlhagen Spot vs Forward and Unadjusted vs Premium-Adjusted delta equations—proving why K_DNS sits ABOVE forward in EUR/USD and BELOW forward in USD/JPY!
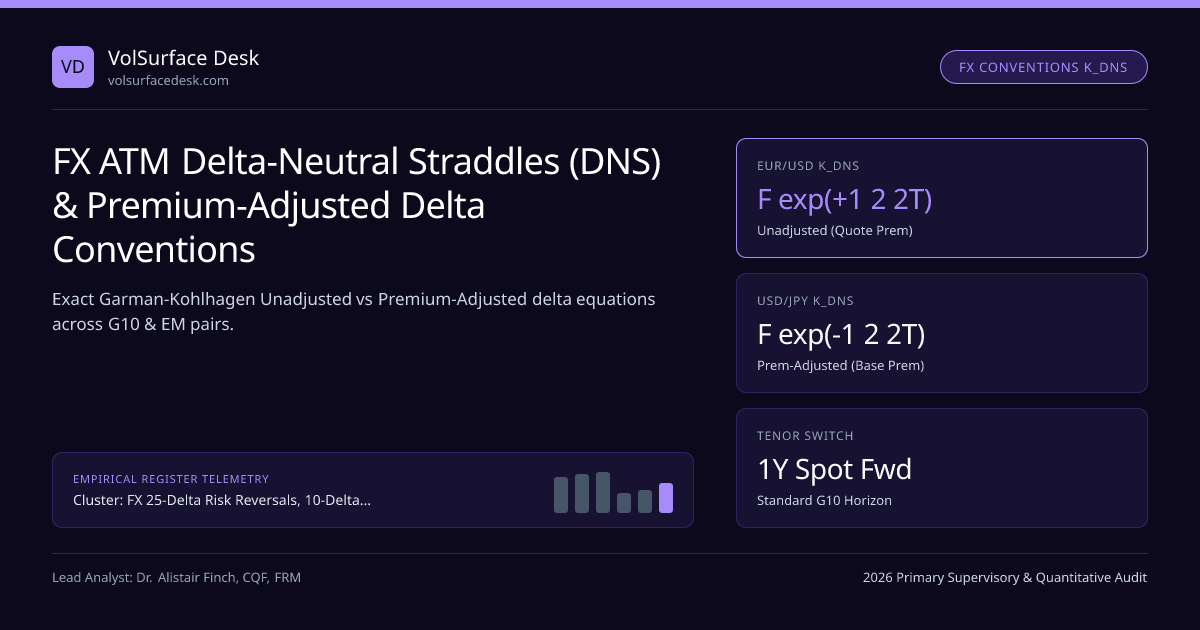
Ask a quantitative developer migrating from equity options to an interbank FX volatility desk to build a surface engine, and 90% of first-draft implementations fail on USD/JPY within five minutes! Why? Because in EUR/USD, the At-the-Money Delta-Neutral Straddle strike KDNS sits above the outright forward F, whereas in USD/JPY KDNS sits below the outright forward F!
Within the FX 25-Delta Risk Reversals, 10-Delta Butterflies & Event Vol Weights silo and our FX Volatility Surfaces & Event Vol Guide, mastering Four FX Delta Conventions (Spot Unadjusted, Forward Unadjusted, Spot Premium-Adjusted, and Forward Premium-Adjusted) is the mandatory foundation before fitting any SABR or SVI smile.
Exact Garman-Kohlhagen Equations for All Four FX Delta Conventions#
For currency pair FOR/DOM with spot S (units of DOM per 1 FOR), domestic rate rd, foreign rate rf, outright forward F = S · exp((rd − rf)T), and Black-76 option value in domestic currency Vdom = e^(−rd T) · [ω·F·N(ω·d1) − ω·K·N(ω·d2)] (ω = +1 call, −1 put), if option premium Vfor = Vdom / S is settled in Foreign (Base) currency, the trader's net FOR exposure is ∂Vdom/∂S − Vdom/S. Algebraic cancellation (F·N(d1) − [F·N(d1) − K·N(d2)] = K·N(d2)) produces a stunningly clean formula:
Quantitative Pricing Model: FX ATM Delta-Neutral Straddles & Premium-Adjusted Delta#
- Forward Delta Variants (Drop e^(−rf·T) Factor for >1Y Tenors): ΔFwdUnadj = ω · N(ω·d1) vs ΔFwd_PremAdj = ω · (K / F) · N(ω·d2)!
- Exact ATM Delta-Neutral Straddle Strike (ΔCall + ΔPut = 0):
- • Unadjusted Pairs (EUR/USD, GBP/USD, AUD/USD): N(d1) = N(−d1) => d1 = 0 => KDNS = F · exp( +1⁄2 · σATM2 · T ) > F!
- • Premium-Adjusted Pairs (USD/JPY, EUR/JPY, USD/CAD, USD/MXN): d2 = 0 => KDNS = F · exp( −1⁄2 · σATM2 · T ) < F!
- Worked 1Y USD/JPY Comparison (S = 152.00, rJPY = 0.45%, rUSD = 4.35% => F = 146.19, σ_ATM = 10.50%, T = 1.0 yr):
- True Prem-Adjusted K_DNS = 146.19 × exp(−0.5 × 0.1052 × 1) = 145.39; Coding Unadjusted by mistake gives 147.00—a massive 161-pip strike error!
Traders verify forward points F − S from dual interest rates in our Futures Fair Value Calculator and check d1 / d2 option sensitivities in the Black-Scholes Option Calculator.
Interbank FX Pair & Tenor Convention Routing Engine#

Standard Interbank Convention Reference Table Across Major FX Pairs#
| Currency Pair | Premium Currency | Delta Adjustment Rule | Tenor ≤ 1Y vs > 1Y | Exact K_DNS Formula |
|---|---|---|---|---|
| EUR/USD, GBP/USD, AUD/USD | USD (Domestic/Quote) | Unadjusted (N(d1)) | Spot Δ (≤1Y), Fwd Δ (>1Y) | F · exp(+1⁄2σ2T) |
| USD/JPY, USD/CHF, USD/CAD | USD (Foreign/Base!) | Premium-Adjusted ((K/F)N(d2)) | Spot Δ (≤1Y), Fwd Δ (>1Y) | F · exp(−1⁄2σ2T) |
| EUR/JPY, EUR/CHF, EUR/GBP | EUR (Foreign/Base!) | Premium-Adjusted ((K/F)N(d2)) | Spot Δ (≤1Y), Fwd Δ (>1Y) | F · exp(−1⁄2σ2T) |
| USD/BRL, USD/TRY, USD/KRW | USD (Foreign/Base!) | Premium-Adjusted | Forward Δ Across ALL Tenors (NDF!) | F · exp(−1⁄2σ2T) (or ATMF) |
25-Delta Call Strike Shift: Unadjusted vs Premium-Adjusted (Pips)#
Notice Bar 4 (σ·√T > 0.26 Dual-Root Hazard): on long-dated or high-vol pairs, ΔPAcall(K) rises from 0 (as K → ∞) up to a peak around K ≈ F · exp(−σ√T) and then drops back toward zero as K → 0! Production root-finders always bracket K25C > KDNS strictly to the right of K_DNS so the Newton solver never lands on the bogus deep-ITM root! Related institutional playbooks include FX 25-Delta Risk Reversals & USD/JPY Carry Skew Guide together with FX Market Strangle (1-Vol) vs Smiley Broker Butterfly Guide.
Frequently asked questions
Why does holding a USD/JPY call create extra delta exposure from the option premium itself?
In USD/JPY, USD is the base ("foreign") currency and JPY is the numeraire ("domestic") currency, yet institutional traders keep their P&L books and pay option premiums in USD! If your USD/JPY call is worth $1,000,000 USD (¥152M JPY), a spot rise increases its JPY mark without changing USD—altering required USD spot hedge by -V_USD!
What is the "non-monotonic call delta paradox" on premium-adjusted FX options?
Because Premium-Adjusted Call Delta equals e^(-r_f T) · [ N(d1) - (V_call / (S · e^(-r_f T))) ] = (K / F) · e^(-r_f T) · N(d2), as strike K drops deep in-the-money toward 0, (K / F) → 0! Thus a deep-ITM premium-adjusted call delta rises to a peak (~0.42 to 0.48 on high-vol EM!) and then FALLS back toward zero!
What happens if a high-volatility EM pair has NO strike reaching 50% premium-adjusted call delta?
Look at Δ_PA_call = e^(-r_d T) · (K/S) · N(d2): when σ√T is huge (e.g., 2Y USD/TRY or USD/BRL), maximum call delta across ALL strikes can sit below 0.50, meaning TWO strikes share 25-delta! That is why ATM is defined via Delta-Neutral Straddle (Δ_call + Δ_put = 0, which ALWAYS has unique root F·e^(-1⁄2σ2T)) rather than "50-delta"!
Which major currency pairs use Unadjusted vs Premium-Adjusted delta in interbank broking?
Pairs with EUR, GBP, AUD, or NZD as base currency against USD (EUR/USD, GBP/USD, AUD/USD, NZD/USD) pay premium in USD (quote currency) => UNADJUSTED delta! Almost all pairs with USD or EUR as base against JPY, CHF, CAD, Nordics, or EM (USD/JPY, EUR/JPY, USD/CAD, USD/MXN) pay premium in base currency => PREMIUM-ADJUSTED delta!
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). FX ATM Delta-Neutral Straddles (DNS) & Premium-Adjusted Delta Conventions. VolSurface Desk. https://volsurfacedesk.com/desk-notes/fx-atm-delta-neutral-straddle-premium-adjusted-deltaRelated FX Risk Reversal Strangle Surfaces & Institutional Briefings
Explore FX Risk Reversal Strangle Surfaces Hub (20) →FX Risk Reversal Strangle Surfaces
FX Volatility Surfaces: 25-Delta Risk Reversals, 10d Butterflies & Event Vol GuideFX Risk Reversal Strangle Surfaces
FX 25-Delta Risk Reversals: USD/JPY & EUR/USD Carry Crash SkewFX Risk Reversal Strangle Surfaces
FX Market Strangle (1-Vol) vs Smiley Broker Butterfly (2-Vol) IterationFX Risk Reversal Strangle Surfaces
Malz Quadratic vs Vanna-Volga FX Volatility Smile InterpolationFX Risk Reversal Strangle Surfaces
FX 10-Delta Wing Butterflies vs 25-Delta Flies: Jump Kurtosis PricingFX Risk Reversal Strangle Surfaces
Overnight FX Central-Bank Event Variance Weights (FOMC, ECB, BoJ)FX Risk Reversal Strangle Surfaces
Sticky-Strike vs Sticky-Delta FX Smiles: Shadow-Delta Hedging MathFX Risk Reversal Strangle Surfaces
Vanna-Volga & First-Exit Attenuation on FX Double-No-Touch (DNT) BarriersIndex Dispersion Correlation Desk
Vega-Neutral vs Theta-Neutral vs Variance-Neutral Dispersion Leg SizingIndex Dispersion Correlation Desk
Mega-Cap Concentration (Top-7 SPX Weights) & COR1M Compression BiasIndex Dispersion Correlation Desk
Pre-Earnings Implied Jump Extraction (σ_earn): Stripping Event VarianceIndex Dispersion Correlation Desk
Correlation-Spike Tail Risk: Why Dispersion Books Bleed in Macro Panics
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.