
Dealer Gamma Vanna Charm Flows
Charm (∂Δ/∂t) Time-Bleed Mechanics: Intraday, Weekend & OPEX Equity Drift
Derive Black-Scholes Charm (∂Δ/∂t) and quantify how deterministic OTM put delta decay drives midday S&P 500 upward drift, Friday afternoon weekend pricing, and OPEX unwinds.
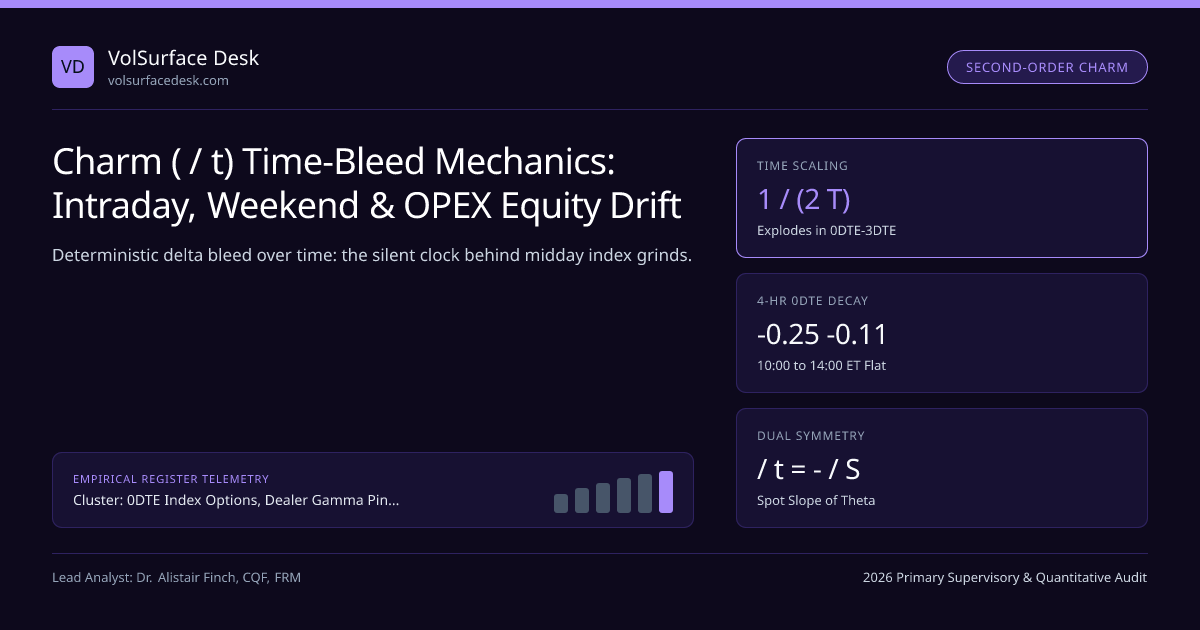
Why does the S&P 500 so frequently stall after an active first hour (09:30–10:30 ET) and then levitate upward in a relentless, low-volatility 15-to-25 point staircase between 10:45 ET and 14:30 ET despite zero breaking news? Within the 0DTE Index Options, Dealer Gamma Pinning, Vanna & Charm Rehedging curriculum and our 0DTE Dealer Gamma, Vanna & Charm Flows Guide, the primary culprit is Charm (∂Δ/∂t)—the deterministic rate at which option deltas decay as expiration approaches.
Analytical Formula and Time-Scaling Asymmetry of Black-Scholes Charm#
Taking the partial derivative of European option delta with respect to passage of time t (equivalently −∂Δ/∂T where T = T_exp − t is remaining variance time) establishes Charm (and its Schwarz identity as the negative spot-gradient of Theta, −∂Θ/∂S):
- Zero-Carry Short-Dated Limit (r ≈ q, T → 0): Charm ≈ +φ(d1) · d2 / (2 · T) ! Notice the 1/(2·T) denominator versus Vanna’s 1/σ scaling!
- Economic Meaning for OTM Puts (K < F => d2 > 0): As clock time advances (Δt > 0), Δ_put moves positively from −0.25 toward 0.00.
- Worked Intraday 0DTE SPX Put Bleed (SPX = 5,850 Flat, K = 5,820 Put, σ = 13.0% Flat):
- At 10:00 ET (T = 6.0 hrs): Δput = −0.246. At 14:00 ET (T = 2.0 hrs): Δput = −0.104! Across 120,000 dealer-short 0DTE puts, dealers must BUY +3,408 CME ES contracts (+$996.8M) over 4 hours with ZERO change in SPX or IV!
Traders evaluate intraday theta and delta drift across custom expiries in our Black-Scholes Option Calculator and Option Greeks & GEX Calculator.
Deterministic Intraday 0DTE Charm Bleed Pipeline (10:00–15:30 ET)#
Why 0DTE–3DTE Dominates Charm While 7DTE–45DTE Dominates Vanna#
Comparing the mathematical denominators of Vanna (∂Δ/∂σ) and Charm (Vanna & Charm Second-Order Hedging Benchmark) unlocks a crucial desk rule for weighting expirations:
- Vanna ∝ d2 / σ: A 30-DTE 25-delta put and a 1-DTE 25-delta put have almost identical standardized d1 and d2 scores! Therefore, large institutional open interest in 14-to-45 DTE monthly options dominates aggregate Vanna during macro volatility crushes.
- Charm ∝ d2 / (2 · T): Because T sits directly in the denominator, a 0.5-day option generates 60 times the hourly Charm per contract of a 30-day option at the same delta! Consequently, 0DTE, 1DTE, and expiring Friday/OPEX weeklies completely dominate intraday Charm drift on Cboe.
Sign Matrix of Dealer Charm Across Portfolio Structures#
Charm is not permanently bullish! Its direction depends strictly on whether dealers are short OTM puts or long OTM puts (such as inventory bought from Systematic Put-Write ETFs (PUTW, XYLD)):
| Market Positioning Regime | Dominant Short-Dated Dealer Book | Hourly Charm Hedge Direction | Observed Tape Signature & Related Desk Note |
|---|---|---|---|
| Macro Fear / Event Overhang | Dealers Short 0DTE–5DTE OTM Puts | Steady ES Buying (+$150M to +$350M/hr) | Classic midday V-bottom & low-vol grind higher |
| Heavy Systematic Put-Write Roll | Dealers Long OTM Puts + Long Calls | Steady ES Selling (−$100M to −$250M/hr) | Heavy midday tape; rallies fade without news |
| Retail Call-Lotto Frenzy | Dealers Short 0DTE OTM Calls | Steady ES Selling as OTM calls decay to 0Δ | Afternoon bleed lower after morning gap-up stalls |
| Pre-OPEX Thursday / Friday | Expiring Monthly Put Skew Unwind | Peak Multi-Billion Unwind into AM SOQ | Post-OPEX "unclenching" window when support vanishes |
Hourly Charm Intensity Across Option Tenors (25-Delta SPX Put)#

Finally, naive traders often compute Friday afternoon Charm using literal 72-hour calendar decay over Saturday and Sunday. As we prove in 0DTE Intraday Variance Clock vs Wall-Clock Theta, institutional pricing engines governed by SEC and OCC valuation standards run on variance-weighted trading clocks, preventing artificial Friday-close delta cliffs.
Frequently asked questions
How fast does Charm decay delta on a 25-delta 0DTE SPX put between 10:00 ET and 14:00 ET?
If SPX spot and implied volatility remain flat, a 25-delta put at 10:00 ET (6 hours left) loses roughly 55% of its remaining variance time by 14:00 ET (2 hours left). Its log-moneyness standardized score d1 grows by 1.49x, collapsing put delta from -0.25 to roughly -0.11 solely from the clock.
Why does Charm peak closer to expiration than Vanna does?
Vanna scales proportionally with √T via φ(d1)·d2/σ, making 7-to-45 DTE tenors huge Vanna contributors. Charm scales inversely with remaining time (∝ 1 / [2·T]), so 0DTE to 5-DTE options dominate aggregate market Charm by an order of magnitude.
Does Friday afternoon see extra Charm buying for Saturday and Sunday?
No—institutional market makers on Cboe price options on a weighted variance-time clock where weekend non-trading hours carry only ~0.35 to 0.50 trading days of variance weight, gradually pulled out between Thursday afternoon and Friday 16:00 ET rather than dumped at once.
Can Charm push the S&P 500 downward instead of upward?
Yes! Whenever spot sits ABOVE a massive cluster of ITM short puts or below heavy short OTM calls—or when dealers are net LONG OTM downside puts bought from systematic put-writers—Charm bleeds positive delta away from dealers, generating steady mechanical ES selling.
Publication record
- Published
- November 14, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). Charm (∂Δ/∂t) Time-Bleed Mechanics: Intraday, Weekend & OPEX Equity Drift. VolSurface Desk. https://volsurfacedesk.com/desk-notes/charm-ddelta-dtime-intraday-weekend-opex-driftRelated Dealer Gamma Vanna Charm Flows & Institutional Briefings
Explore Dealer Gamma Vanna Charm Flows Hub (20) →Dealer Gamma Vanna Charm Flows
0DTE Index Options, Net Dealer Gamma (GEX), Vanna & Charm Rehedging Flows GuideDealer Gamma Vanna Charm Flows
Vomma (Volga, ∂2V/∂σ2) Wing Convexity: Why Short 5-Delta Strangles Blow UpDealer Gamma Vanna Charm Flows
Speed (∂Γ/∂S) Third-Order Gamma Gradients & 0DTE Iron Condor Strike CliffsDealer Gamma Vanna Charm Flows
Zomma (∂Γ/∂σ) Mechanics: How Implied Volatility Shocks Mutate Dealer GammaDealer Gamma Vanna Charm Flows
Color (∂Γ/∂t) Gamma Decay vs Final-Hour 0DTE ATM Pin Risk Before 16:00 ETDealer Gamma Vanna Charm Flows
Institutional Quarterly Equity Collar Rolls (JPM HEQT) & Strike PinningDealer Gamma Vanna Charm Flows
Nasdaq-100 (NDX & QQQ) vs S&P 500 (SPX) 0DTE Gamma Pinning & Vol SpreadsDealer Gamma Vanna Charm Flows
OCC STANS 20-Minute Intraday Risk Snapshots & 0DTE Margin Add-OnsVix Futures Variance Swap Convexity
Capped (2.5× Strike) vs Uncapped Variance Swaps: Left-Tail Gap RiskVix Futures Variance Swap Convexity
Corridor Variance & Conditional Down-Variance Swaps: Targeted Crash HedgesVix Futures Variance Swap Convexity
Cboe VVIX Vol-of-Vol & Jensen’s Inequality: The VIX Futures Convexity WedgeVix Futures Variance Swap Convexity
VIX 1×2 Call Ratios & Collars vs Direct SPX OTM Put Tail Hedges
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.