
Dealer Gamma Vanna Charm Flows
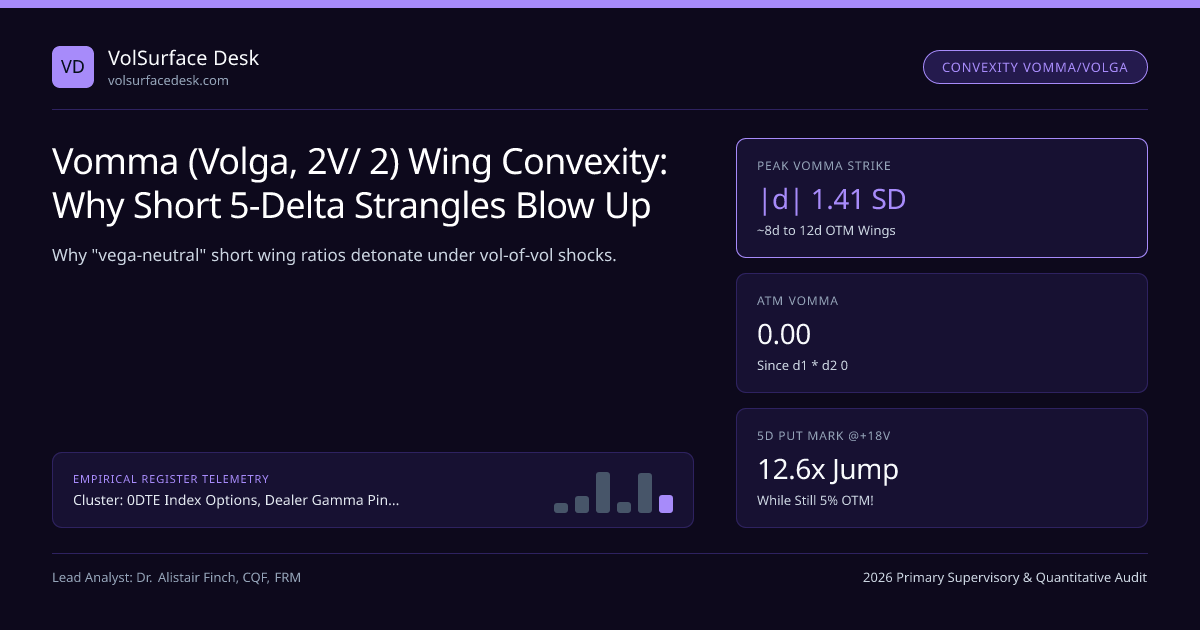
Vomma (Volga, ∂2V/∂σ2) Wing Convexity: Why Short 5-Delta Strangles Blow Up
Analyze Black-Scholes Vomma (Volga, ∂2V/∂σ2) across option moneyness to understand why short 5-delta and 10-delta index strangles detonate during vol-of-vol spikes long before spot hits strikes.
Every multi-year bull cycle lures yield-hungry accounts into selling 30-DTE 5-delta to 10-delta S&P 500 strangles or 1×4 put ratio backspreads, seduced by 94% historical win rates and tiny initial Black-Scholes Vega. Then a sudden geopolitical shock or macro liquidity air-pocket lifts Cboe VVIX (Vol-of-Vol) above 145: although the S&P 500 has fallen only −3.2% and sits 300 points above the short put strikes, the account receives an immediate liquidation notice! Within the 0DTE Index Options, Dealer Gamma Pinning, Vanna & Charm Rehedging framework and our 0DTE Dealer Gamma, Vanna & Charm Flows Guide, this catastrophe is governed by Vomma (also called Volga, ∂2V/∂σ2).
Exact Mathematical Derivation and the √2-Sigma Peak of Vomma#
Differentiating Black-Scholes Vega (ν = S · e^(−qT) · √T · φ(d1)) with respect to implied volatility σ yields Vomma (Vomma, Zomma & Speed Mechanics):
- ATM Null Zone (F ≈ K): d1 = +1⁄2σ√T and d2 = −1⁄2σ√T => d1·d2 = −1⁄4σ2T ≈ 0 (slightly negative!). ATM options have almost ZERO Vomma!
- Wing Peak Zone: Setting ∂[z2 · φ(z)] / ∂z = 0 gives |z*| = √2 ≈ 1.414 SD (~8-delta to 10-delta OTM), where Vomma reaches maximum dollar convexity!
- Worked "Vega-Neutral" 30-DTE SPX Put Ratio Trap (SPX = 5,850, T = 0.0822 yr):
- Buy 1× ATM 5,850 Put (σ = 14.5%, Vega = +$6.68, Vomma = −$0.04) vs Sell 3.4× OTM 5,300 Puts (5d, σ = 21.0%, Vega = −$1.96 each => Net Vega = $0.00, Net Vomma = −$4.82/vol2). Under a −2.5% dip + +14v skew jump, long ATM gains +$148 while 3.4× short wings lose −$592 => Net P&L = −$44,400 per 1-lot!
Traders test large parallel and skew volatility shocks directly in our Black-Scholes Option Calculator and Implied Volatility Calculator.
Anatomy of a Short-Wing Vomma Liquidation Cascade#
Why Vanna-Volga Pricing Exists: Smile Butterflies as Vomma Compensation#
In FX and equity exotic desks, why does a market-quoted 10-delta butterfly trade at a substantial implied-volatility premium over ATM volatility even when Underlying returns look continuous? Consider the full stochastic-volatility Itô-Taylor expansion of a delta- and ATM-vega-hedged option book:
E[dPnL_hedged] = 1⁄2 · Γ · (dS2 − σ2S2dt) + Vanna · dS · dσ + 1⁄2 · Vomma · dσ2
Because (dσ)2 > 0 whenever implied volatility is stochastic (VVIX Vol-of-Vol Benchmark), any option strike with Vomma > 0 (8d–15d wings) enjoys positive expected convexity gains from pure volatility fluctuations! Market makers on Cboe refuse to give away positive 1⁄2 · Vomma · E[dσ2] for free—they mark up 10d and 5d wing implied volatilities until negative theta compensates for expected Vomma gains. Conversely, retail traders who sell those wings collect pennies of daily theta in exchange for underwriting uncapped −1⁄2 · |Vomma| · (Δσ)2 convexity liabilities!
Comparing Option Structures Across Vega, Vomma, and Margin Stress#
| Portfolio Structure (30-DTE SPX) | Initial Net Vega | Net Dollar Vomma | Behavior Under −3% SPX / +12v VVIX Spike | Clearing & Margin Gate |
|---|---|---|---|---|
| Short 5-Delta Strangle | Moderate Negative | Extreme Negative | Catastrophic nonlinear mark loss; Vega triples mid-move | FINRA Rule 4210 TIMS |
| Long ATM / Short 3.4× 5d Put Ratio | Zero (Vega-Flat) | Severe Negative | Loses heavily despite zero initial Vega due to 1⁄2·Vomma·(Δσ)2 | OCC STANS Intraday |
| Long 25d / Short ATM Put Backspread | Moderate Positive | Strong Positive | Explosive convex payoff as wing Vega expands into selloff | Black-Scholes Calculator |
| Iron Condor (Short 10d / Long 5d) | Mild Negative | Capped Negative | 5d long wing carries higher Vomma per dollar, capping tail | Option Greeks Calculator |
Black-Scholes Dollar Vomma Distribution Across Moneyness#
Institutional prime brokers supervised by SEC and FINRA enforce stressed-volatility scan grids inside FINRA Rule 4210 TIMS Portfolio Margin specifically to catch short-Vomma ratios before clearing members face insolvency.
Frequently asked questions
At what option delta does Black-Scholes dollar Vomma reach its maximum?
Because Vomma equals Vega × (d1 · d2 / σ) and Vega follows φ(d1) while d1·d2 ≈ z2, the product z2 · φ(z) peaks mathematically at |z| = √2 ≈ 1.414 standard deviations—corresponding directly to roughly 8-delta to 12-delta out-of-the-money wings!
Why did Volmageddon-style short-strangle funds blow up when spot was still 6% above their put strikes?
A 30-DTE 5-delta SPX put priced at $2.10 when IV = 14% has tiny initial Vega ($1.95/pt). When a -3% SPX drop spikes wing IV from 14% to 32%, positive Vomma expands that put’s Vega from $1.95 to $9.80, inflating the option mark from $2.10 to $26.50 (~12.6x!) while still 5% OTM.
How do institutional volatility desks hedge short Vomma on index ratio spreads?
Linear Vega hedging with ATM options or VIX futures fails because ATM options carry near-zero Vomma. Desks hedge wing Vomma using far-OTM VIX calls (capturing VVIX convexity), 2-delta SPX "teenies" tail units, or capped variance swaps.
Why do market makers charge a positive butterfly premium above Black-Scholes flat-vol pricing?
Under stochastic vol-of-vol, an option portfolio with positive Vomma earns positive expected mark-to-market convexity 1⁄2 · Vomma · (dσ)2 > 0 whenever implied volatility fluctuates. Market makers raise wing implied volatilities (creating the smile butterfly) precisely to charge for Vomma!
Publication record
- Published
- November 14, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). Vomma (Volga, ∂2V/∂σ2) Wing Convexity: Why Short 5-Delta Strangles Blow Up. VolSurface Desk. https://volsurfacedesk.com/desk-notes/vomma-volga-wing-convexity-short-strangle-blowupsRelated Dealer Gamma Vanna Charm Flows & Institutional Briefings
Explore Dealer Gamma Vanna Charm Flows Hub (20) →Dealer Gamma Vanna Charm Flows
0DTE Index Options, Net Dealer Gamma (GEX), Vanna & Charm Rehedging Flows GuideDealer Gamma Vanna Charm Flows
Speed (∂Γ/∂S) Third-Order Gamma Gradients & 0DTE Iron Condor Strike CliffsDealer Gamma Vanna Charm Flows
Zomma (∂Γ/∂σ) Mechanics: How Implied Volatility Shocks Mutate Dealer GammaDealer Gamma Vanna Charm Flows
Color (∂Γ/∂t) Gamma Decay vs Final-Hour 0DTE ATM Pin Risk Before 16:00 ETDealer Gamma Vanna Charm Flows
Institutional Quarterly Equity Collar Rolls (JPM HEQT) & Strike PinningDealer Gamma Vanna Charm Flows
Nasdaq-100 (NDX & QQQ) vs S&P 500 (SPX) 0DTE Gamma Pinning & Vol SpreadsDealer Gamma Vanna Charm Flows
OCC STANS 20-Minute Intraday Risk Snapshots & 0DTE Margin Add-OnsDealer Gamma Vanna Charm Flows
FINRA Rule 4210 TIMS Portfolio Margin vs Reg T Haircuts for Index BooksVix Futures Variance Swap Convexity
Corridor Variance & Conditional Down-Variance Swaps: Targeted Crash HedgesVix Futures Variance Swap Convexity
Cboe VVIX Vol-of-Vol & Jensen’s Inequality: The VIX Futures Convexity WedgeVix Futures Variance Swap Convexity
VIX 1×2 Call Ratios & Collars vs Direct SPX OTM Put Tail HedgesVix Futures Variance Swap Convexity
Ultra-Short VIX1D vs VIX9D, VIX & VIX3M Event Term-Structure Kinks
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.