
Vix Futures Variance Swap Convexity
CFE & OCC VIX Futures–Options Cross-Margining & Capital Optimization
Solve the SEC-vs-CFTC regulatory silo split on volatility books: learn how OCC clears BOTH CFE VIX futures and Cboe SPX/VIX options—enabling 65%–85% STANS cross-margin offsets on hedged volatility arbitrage!
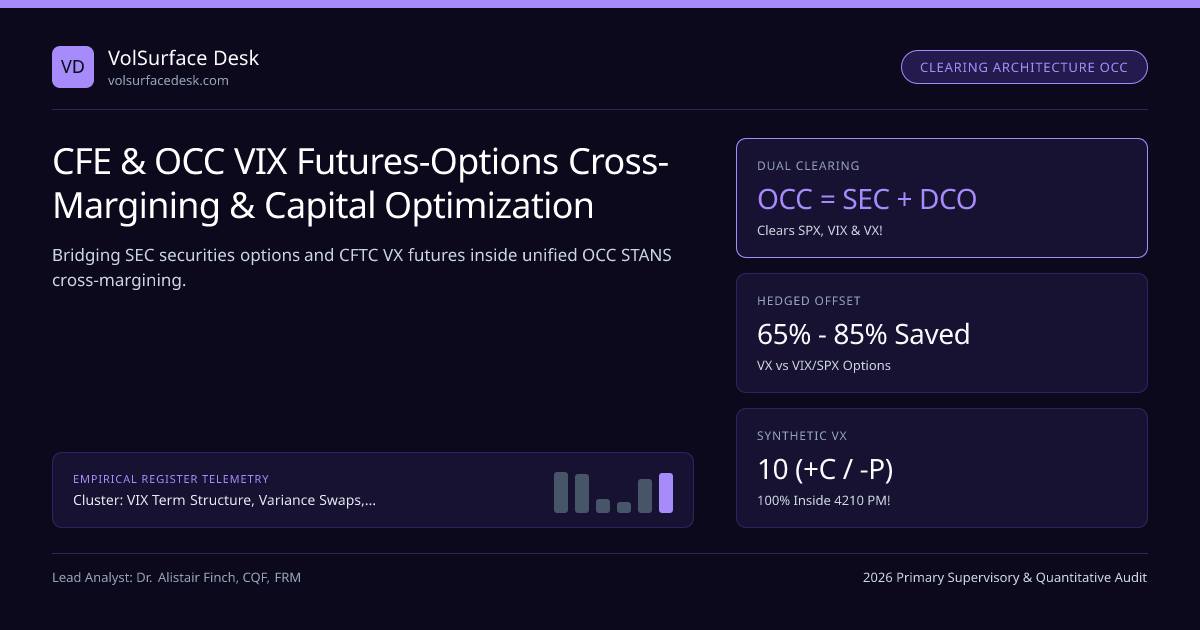
Ask a newly launched volatility hedge fund why their ROE lagged projections by 800 bps in Year 1, and the culprit is frequently regulatory margin siloing. In the United States, Cboe VIX Options and SPX Options are classified as securities regulated by the SEC, whereas Cboe Futures Exchange (CFE) VX Futures are classified as futures regulated by the CFTC! If you hold your VIX options in a standard securities sleeve and your VX futures hedge in a segregated futures sleeve, neither risk engine sees the other—charging double collateral on a tightly hedged arbitrage book!
Within the VIX Term Structure, Variance Swaps, Vol-of-Vol VVIX & Tail Hedging silo and our VIX, Variance Swaps & Tail Hedging Guide, solving this capital bottleneck relies on a unique institutional advantage: the Options Clearing Corporation (OCC) clears BOTH Cboe options AND CFE VX futures (OCC STANS Methodology Benchmark).
Quantifying Siloed Margin Penalty vs Unified OCC Cross-Margining & Synthetic VX#
Consider a volatility market maker or RV pod trading the VVIX Convexity Basis or delta-hedging VIX call skew: Short 1,000 VIX 22 Calls (Δ = +0.45, $100 mult) delta-hedged with Long 45 CFE VX Futures ($1,000 mult):
Quantitative Pricing Model: CFE & OCC VIX Cross-Margining & Capital Efficiency Guide#
- Contract Multiplier Identity: 1 CFE VX Future ($1,000/pt) ≡ 10 Cboe VIX Option Combos ($100/pt × 10 = $1,000/pt)!
- Synthetic VX Future Inside FINRA 4210 PM (Zero Futures Segregation Needed!): Long 10 VIX(K) Calls + Short 10 VIX(K) Puts = Exact $1,000/pt Forward F_VX = K + e^(rT)·(C − P)!
- Worked Capital Efficiency Audit (VX2 = 17.50, Short 1,000 VIX 22 Calls @ $1.85 + Long 45 VX2 Futures):
- • Siloed Split Accounts: Uncovered VIX Calls ($1,980,000) + Standalone 45 VX SPAN Margin ($337,500) = $2,317,500 Total Margin!
- • Unified OCC Cross-Margin (or Synthetic VX Combo in FINRA 4210 PM): Delta cancels 100%, leaving bounded gamma/vomma => Required Margin = $485,000 (79.1% capital reduction = 4.78x higher return on equity!).
Traders verify exact Black-76 VIX call/put parity and combo deltas in our Black-Scholes Option Calculator and Option Greeks & GEX Calculator.
Eliminating SEC / CFTC Margin Silos on VIX & SPX Volatility Books#
Comparing Clearing & Cross-Margin Pathways Across Volatility Trades#
| Volatility Arbitrage Book | Instruments Combined | Optimal Clearing / Margin Structure | Typical Margin Offset Achieved |
|---|---|---|---|
| VIX Option Market Making | CFE VX Futures + Cboe VIX Options | OCC Internal Cross-Margin (or 10× VIX Combo in 4210 PM) | 75% – 85% delta/vega offset |
| Wednesday VRO Basis Strip | CFE VX1 Future vs 30d SPX 1/K2 Strip | OCC Cross-Margin (both clear natively at OCC!) | 70% – 82% variance-strip offset |
| SPX Gamma vs CME ES Futures | Cboe SPX Options vs CME ES Futures | OCC–CME Cross-Margining Agreement (Clearing Member / Market Maker) | 80% – 90% index delta offset |
| Cross-Atlantic FVS vs VX | Eurex FVS (Prisma) vs CFE VX (OCC) | Separate clearinghouses (Eurex Clearing vs OCC); 0% cross-CCP offset! | 0%—size cash buffers for FX + VM! |
Collateral Locked ($k) on a $100k-Vega Hedged VIX Skew Book#
Look at Bar 3 (4210 PM + VIX Combos = $540k): for sub-$100M hedge funds and prop desks that do not yet have a custom dual-registered OCC Cross-Margin facility, replacing outright Cboe VX futures with 10-lot European VIX Call-Put Synthetic Combos inside a standard FINRA Rule 4210 Portfolio Margin account captures 95% of institutional cross-margin efficiency on Day 1!
Frequently asked questions
Why does OCC clear CFE VIX futures when CME clears S&P 500 ES futures?
Cboe Futures Exchange (CFE) is a wholly owned CFTC-designated contract market of Cboe Global Markets that selected the Options Clearing Corporation (OCC)—registered simultaneously as an SEC Clearing Agency and a CFTC Derivatives Clearing Organization (DCO)—as its native clearinghouse!
Why don’t retail accounts automatically get cross-margining between VX futures and VIX options?
Because SEC Rule 15c3-3 (Customer Protection) and CFTC Section 4d (Futures Segregation) segregate retail customer cash into legally separate bankruptcy pools unless the broker-dealer/FCM maintains a joint SEC/CFTC cross-margining program or Portfolio Margin prime-brokerage wrapper!
How can a FINRA Rule 4210 Portfolio Margin account synthesize a VX future without a CFTC futures account?
By Put-Call Parity on European VIX options! Buying 10 VIX 20.00 Calls and Selling 10 VIX 20.00 Puts of the exact same expiration replicates +1 CFE VX future ($1,000/pt notional since 10 × $100 = $1,000!) 100% INSIDE the SEC securities account—capturing full TIMS/STANS margin offset immediately!
How much margin offset does OCC STANS grant between short SPX puts and short VIX futures? Wait—do those offset or compound?
They COMPOUND! Short SPX puts AND short VX futures are BOTH short volatility—STANS charges additive tail risk! Conversely, LONG VX futures against SHORT SPX puts (or Short VX futures against Long VIX calls / Long SPX variance strips) receives 65% to 85% risk offset!
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). CFE & OCC VIX Futures–Options Cross-Margining & Capital Optimization. VolSurface Desk. https://volsurfacedesk.com/desk-notes/cfe-occ-vix-futures-options-cross-margining-capitalRelated Vix Futures Variance Swap Convexity & Institutional Briefings
Explore Vix Futures Variance Swap Convexity Hub (20) →Vix Futures Variance Swap Convexity
VIX Term Structure, OTC Variance Swaps, VVIX Vol-of-Vol & Tail Hedging GuideVix Futures Variance Swap Convexity
Cboe VIX Model-Free Log-Strip Replication & Strike Truncation BiasVix Futures Variance Swap Convexity
VIX Futures M1–M2 Contango Roll Bleed & Curve Carry HarvestingVix Futures Variance Swap Convexity
VIX Term-Structure Backwardation, Spot-to-VX Beta & Panic Mean ReversionVix Futures Variance Swap Convexity
OTC S&P 500 Variance Swaps: Vega-to-Variance Notional & Convexity MathVix Futures Variance Swap Convexity
Capped (2.5× Strike) vs Uncapped Variance Swaps: Left-Tail Gap RiskVix Futures Variance Swap Convexity
Corridor Variance & Conditional Down-Variance Swaps: Targeted Crash HedgesVix Futures Variance Swap Convexity
Cboe VVIX Vol-of-Vol & Jensen’s Inequality: The VIX Futures Convexity WedgeIndex Dispersion Correlation Desk
Cboe COR1M & COR3M Implied Correlation Indices: Top-50 SPX Math & SignalsIndex Dispersion Correlation Desk
Vega-Neutral vs Theta-Neutral vs Variance-Neutral Dispersion Leg SizingIndex Dispersion Correlation Desk
Mega-Cap Concentration (Top-7 SPX Weights) & COR1M Compression BiasIndex Dispersion Correlation Desk
Pre-Earnings Implied Jump Extraction (σ_earn): Stripping Event Variance
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.