
Vix Futures Variance Swap Convexity
Spot-Weighted Gamma Swaps vs Variance Swaps: Taming Crash Truncation
Discover why institutional single-stock and dispersion desks trade OTC Gamma Swaps: weighting daily variance by S_t / S_0 replaces 1/K2 replication with gentle 1/K weights—automatically damping bankruptcy crash explosions!
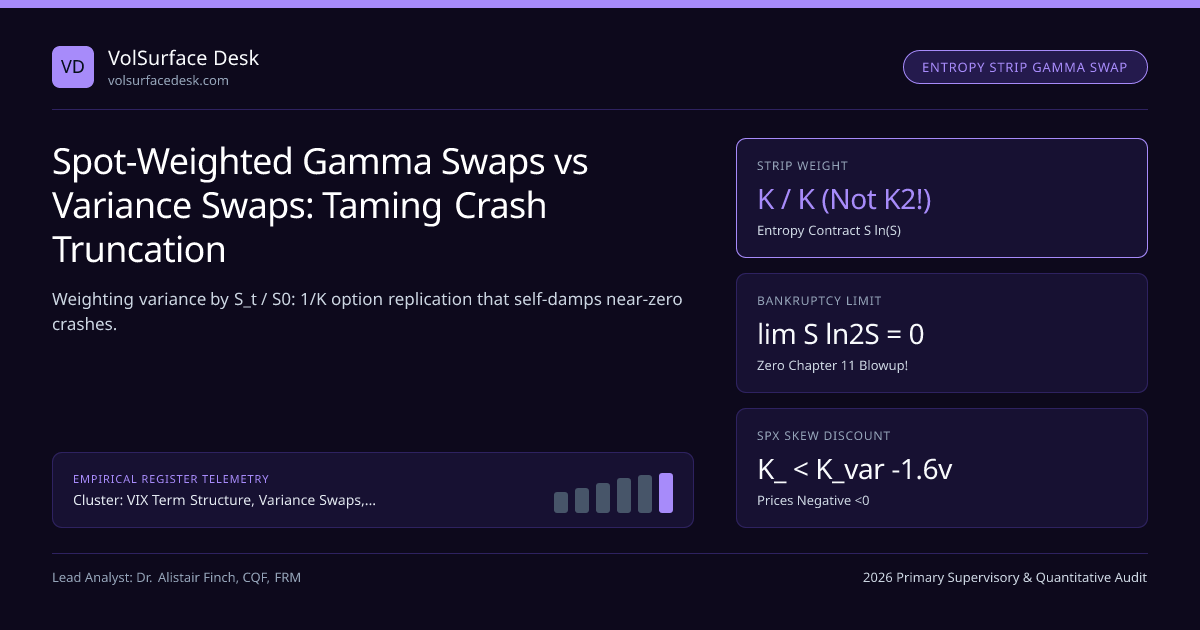
Recall the fatal flaw of uncapped single-stock variance swaps exposed in Capped (2.5×) vs Uncapped Variance Swaps: weighting option strikes by 1 / K2 blows up near K → 0, while imposing a hard 2.5× cap breaks static model-free replication! Is there a continuous, 100% statically replicable variance derivative that naturally damps crash singularities as S_t → 0 without any artificial path-dependent cap? Yes—the OTC Spot-Weighted Gamma Swap!
Within the VIX Term Structure, Variance Swaps, Vol-of-Vol VVIX & Tail Hedging silo and our VIX, Variance Swaps & Tail Hedging Guide, Gamma Swaps power institutional single-stock dispersion and Implied-vs-Realized Skew trading (OTC Variance & Corridor Benchmark).
Exact Entropy-Contract Replication (1/K Strip) and Skew-Swap Difference#
Weighting each day's squared log-return by the spot level Si / S0 yields Realized Gamma-Swap Variance. Applying Itô's lemma to the **entropy contract ST · ln(ST / F0) − (ST − F0) whose second derivative is g''(K) = 1 / K proves exact model-free static replication across OTM puts and calls weighted by ΔK / K** (instead of ΔK / K2!):
Quantitative Pricing Model: Spot-Weighted Gamma Swaps vs Variance Swaps Guide#
- Self-Damping Bankruptcy Property: As Si → 0, (Si / S0) · [ln(Si / S{i−1})]2 → 0 smoothly—eliminating Chapter 11 variance explosions without breaking static option replication!
- Pure Leverage/Skewness Swap (Long $1 Var Swap − Short $1 Gamma Swap): Payoff = Σ [ 1 − (Si / S0) ] · ri2 − (Kvar2 − Kgamma2)!
- Worked SPX 6-Month Skew-Swap Valuation (SPX S0 = 5,850, Kvar = 16.40v [268.96 var], Kgamma = 14.85v [220.52 var]):
- Implied Skew Wedge = Kvar − Kgamma = +1.55 vol pts (+48.44 var pts)! If SPX drops −18% (avg S_i/S0 = 0.88) at 34v realized vol (1,156 var): Realized Wedge = (1 − 0.88) × 1,156 = +138.7 var pts vs 48.4 paid => +90.3 var pts profit!
Traders inspect 1/K versus 1/K2 strike weightings across Cboe SPX puts and calls using our Black-Scholes Option Calculator and Option Greeks & GEX Calculator.
From Variance & Gamma Swaps to Pure Realized Skew Trading#
Comparing Variance Swaps, Capped Variance, and Gamma Swaps#
| Contract Architecture | Option Strip Weight w(K) | Behavior in −90% Single-Stock Crash | Behavior in +60% Upside Squeeze |
|---|---|---|---|
| Uncapped Variance Swap | 1 / K2 | Catastrophic blowup (>10,000 var pts); unhedgeable | Standard r_i2 accrual |
| 2.5× Capped Variance Swap | Dynamic PDE + 1/K2 | Hard ceiling at 6.25 · K2; loses static hedge | Capped at 6.25 · K2 |
| Spot-Weighted Gamma Swap | 1 / K (Exact Static!) | Self-damps smoothly as S_i / S0 → 0.10! | Amplifies upside variance by 1.60×! |
| Skew Swap (Var − Gamma) | (F0 − K) / (F0 · K2) | Positive payout (1 − S_i/S0 > 0) | Negative payout (1 − S_i/S0 < 0) |
Asymmetric Variance Accrual: Variance Swap vs Gamma Swap#
Notice Bar 4 (+45% Momentum Rally): for hedge funds seeking upside volatility convexity on AI/semiconductor leaders without overpaying for downside bankruptcy puts, buying a single-stock Gamma Swap costs less upfront and automatically scales up vega exposure as the stock rallies!
Frequently asked questions
Why is a Spot-Weighted Variance Swap called a "Gamma Swap"?
Recall that a standard variance swap maintains constant DOLLAR gamma ($Γ = S2 · Γ = constant) regardless of where spot moves. Multiplying by S_t / S_0 means dollar gamma scales linearly with spot S_t—mimicking the natural cash-equity value scaling of an un-rebalanced portfolio without crashing to infinity near zero!
Why does a Gamma Swap strike ALWAYS trade LOWER than an S&P 500 Variance Swap strike?
In equity markets with negative spot-vol correlation (ρ ≈ -0.75), variance spikes when S_t < S_0 (downweight < 1.0!) and compresses when S_t > S_0 (upweight > 1.0!). Equivalently, 1/K weights cheap upside calls more and expensive downside puts less than 1/K2, pricing K_gamma 1.1 to 2.6 vol points BELOW K_var!
Does a single-stock Gamma Swap require an artificial 2.5x volatility cap to prevent bankruptcy blowups?
Mathematically no! Because lim_{S→0} S · (ln S)2 = 0 by L’Hôpital’s rule, even a literal -99.9% overnight Chapter 11 wipeout produces strictly finite, self-damping Gamma Swap accrual—avoiding the unhedgeable deep-put truncation cliff of uncapped variance swaps!
How do exotic desks trade pure equity spot-vol correlation using Variance minus Gamma Swaps?
Look at Payoff(Var Swap) - Payoff(Gamma Swap) = Σ (1 - S_i / S_0) · r_i2! Whenever a crash drives S_i < S_0 simultaneously with high r_i2, (1 - S_i/S_0) > 0 generates positive payout; if volatility spikes during an upside rally (S_i > S_0), it pays negatively—a pure trade on implied vs realized skew!
Publication record
- Published
- November 13, 2026
- Updated
- November 15, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 15). Spot-Weighted Gamma Swaps vs Variance Swaps: Taming Crash Truncation. VolSurface Desk. https://volsurfacedesk.com/desk-notes/gamma-swaps-spot-weighted-variance-skew-hedgingRelated Vix Futures Variance Swap Convexity & Institutional Briefings
Explore Vix Futures Variance Swap Convexity Hub (20) →Vix Futures Variance Swap Convexity
VIX Term Structure, OTC Variance Swaps, VVIX Vol-of-Vol & Tail Hedging GuideVix Futures Variance Swap Convexity
CFTC Traders in Financial Futures (TFF) VIX Positioning & Squeeze SignalsVix Futures Variance Swap Convexity
CFE & OCC VIX Futures–Options Cross-Margining & Capital OptimizationVix Futures Variance Swap Convexity
Cboe VIX Model-Free Log-Strip Replication & Strike Truncation BiasVix Futures Variance Swap Convexity
VIX Futures M1–M2 Contango Roll Bleed & Curve Carry HarvestingVix Futures Variance Swap Convexity
VIX Term-Structure Backwardation, Spot-to-VX Beta & Panic Mean ReversionVix Futures Variance Swap Convexity
OTC S&P 500 Variance Swaps: Vega-to-Variance Notional & Convexity MathVix Futures Variance Swap Convexity
Capped (2.5× Strike) vs Uncapped Variance Swaps: Left-Tail Gap RiskFX Risk Reversal Strangle Surfaces
Calibrating Stochastic Local Volatility (Heston-SLV) to FX Surfaces & BarriersFX Risk Reversal Strangle Surfaces
ISDA SIMM Initial Margin for OTC FX Options: Vega & Curvature BucketsIndex Dispersion Correlation Desk
Cboe COR1M & COR3M Implied Correlation Indices: Top-50 SPX Math & SignalsIndex Dispersion Correlation Desk
Vega-Neutral vs Theta-Neutral vs Variance-Neutral Dispersion Leg Sizing
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.