
Index Dispersion Correlation Desk
OTC Clean Correlation Swaps vs Option-Strip "Dirty" Dispersion Mechanics
Why did a portfolio manager who accurately predicted realized S&P 500 correlation of 14% against 24% implied correlation STILL lose money on a 90-day ATM straddle dispersion basket? Meet Path-Dependent Gamma Drift ("Dirty Dispersion").
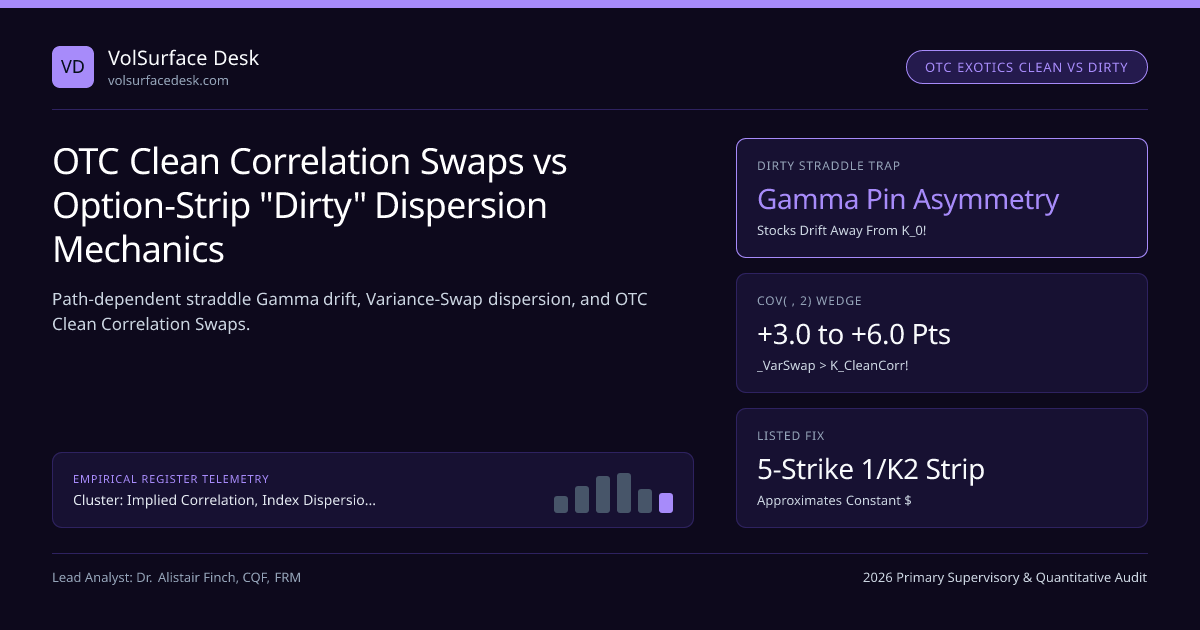
Imagine forecasting S&P 500 correlation to perfection: you enter a 90-day Index Dispersion trade when implied correlation sits at 24.0%, over the next 90 days realized pairwise correlation prints 15.2%, and yet at expiration your delta-hedged ATM straddle P&L statement shows a net loss of −$180,000! Every veteran volatility trader has witnessed this shock first-hand. The culprit is Path-Dependent Gamma Drift—the mathematical chasm separating Dirty Straddle Dispersion, OTC Variance-Swap Dispersion, and OTC Clean Correlation Swaps.
Within our Implied Correlation, Index Dispersion Baskets & Earnings Vol Crush silo and Dispersion Desk Manual, mastering these three instruments ensures your trade structure actually pays out on your correlation thesis.
Exact Payoff & Convexity Hierarchy: Clean Correlation vs Variance vs Straddles#
Compare the exact realized P&L equations across the three dispersion implementations over [0, T]:
- Where Clean Realized Pairwise Correlation is ρreal = [ ∑{i ≠ j} wi · wj · Corr(ri, rj) ] / [ ∑{i ≠ j} wi · w_j ], completely independent of volatility level σ̄!
- Crucial Convexity Wedge Between Variance-Implied ρvar and Clean Correlation Swap Fair Strike Kcorr = E^Q[ρ_real]:
- Since E^Q[σI2] ≈ E^Q[ρ · σ̄2] = E^Q[ρ] · E^Q[σ̄2] + Cov^Q(ρ, σ̄2), dividing by E^Q[σ̄2] proves: ρvarimp − Kcorr ≈ Cov^Q(ρ, σ̄2) / E^Q[σ̄2] > 0 (+3.0 to +6.0 Corr Pts!!).
- Dirty ATM Straddle Path-Dependency Formula: P&LStraddle = ∫0T 1⁄2 · [ ∑ wi Si,t2 Γi(Si,t, Ki,0) (σi,t2 − σ̂i2) − SI,t2 ΓI(SI,t, KI,0) (σI,t2 − σ̂I2) ] dt!
- Notice Γi(Si,t, Ki,0) → 0 if stock i trends ±20% away from Ki,0 in Month 1, while ΓI(SI,t, KI,0) EXPLODES as T → 0 if SPX stays pinned near KI,0!
Simulate how fast single-stock Dollar Gamma decays when spot moves ±15% away from strike versus an pinned ATM index straddle in our Option Greeks & GEX Calculator and Black-Scholes Calculator.
How "Dirty" Fixed-Strike Straddle Dispersion Loses Despite Low Correlation#
Eliminating Path Drift on Listed OPRA Desks: Re-Striking vs 5-Strike Strips#
How do multi-strategy listed-options pods eliminate that toxic Month-3 SPX Pin Gamma asymmetry without paying a bank exotic desk 3.0 correlation points of bid-offer for an ISDA swap? Two battle-tested protocols solve it:
- Delta-Corridor Re-Striking: Whenever any constituent straddle's net underlying move pushes its call delta above 0.75 or below 0.25, roll that single-stock straddle back to the current ATM strike (locking in intrinsic gain and restoring full ATM Dollar Gamma!), AND close or roll the entire dispersion package at 14 DTE before SPX 1/√(T−t) pin Gamma goes parabolic!
- 5-Strike 1/K2 Mini-Variance Strips: Instead of concentrating 100% of vega on the single 50-delta ATM strike, split vega across 15d Put, 30d Put, 50d Straddle, 30d Call, and 15d Call weighted inversely by strike squared (1/K2). Across a ±22% constituent trading corridor, total portfolio Dollar Gamma stays flat within ±7%!
Instrument Comparison: Dirty Straddles vs Mini-Strips vs Variance vs Clean Correlation Swaps#
| Dispersion Vehicle | Execution Venue & Margin | Dollar Gamma Path Profile | Variance × Correlation Convexity | Typical Institutional Use Case |
|---|---|---|---|---|
| 1-Strike ATM Straddle ("Dirty") | Cboe + OPRA (FINRA 4210 PM) | Severe Strike Drift (Requires Re-Striking & 14-DTE Exit) | Exposed to Spot Path + Pin Timing | 14-to-35 day tactical earnings & event dispersion |
| 5-Strike 1/K2 Listed Mini-Strip | Cboe + OPRA Complex Books | Flat $Γ across ±22% spot corridor! | Variance-weighted (ρ_imp includes Skew Wedge) | Core 45-to-90 day listed pod dispersion |
| OTC Variance-Swap Dispersion | ISDA Dealer Desk (CFTC / SEC SBS) | Exact Constant $Γ across all spot levels | Variance-weighted (Bleeds hard if ρ & σ2 spike together!) | Pension & hedge-fund systematic variance harvesting |
| OTC Clean Correlation Swap | Tier-1 Exotic Bank ISDA | Zero Spot/Gamma Path Dependency! | Pure Linear ρreal − Kcorr (No σ̄2 blowup multiplier!) | Pure macro correlation overlay & exotic structured-note hedge |
Same-Day Fair Quote Ladder Across Four Correlation Definitions (90d SPX)#
Next across Silo 5, we expand beyond single-tier SPX-versus-stocks into Two-Tier Sector ETF Dispersion, PEAD Post-Earnings Vol Crush, Hard-to-Borrow Repo Traps, Nasdaq-100 AI Dispersion, Worst-of Autocallables, Ex-Dividend Early Exercise, Cross-Index Arbitrage, 0DTE Intraday Dispersion, FINRA 4210 Margin, and M&A Bimodal Smiles!
Frequently asked questions
How can an ATM straddle dispersion trade lose money when realized correlation is LOWER than implied correlation?
Suppose in Month 1 stocks diverge wildly (zero correlation!) so NVDA rallies +25% and UNH drops −25% while SPX stays at 0%. Month 1 makes money—but now NVDA and UNH sit 25% away from their fixed initial straddle strikes with near-zero Gamma! If in Month 2 SPX whipsaws ±1.8% daily right around its initial ATM strike, your short SPX straddle bleeds peak Gamma while your dead OTM stock straddles earn nothing!
Why does Variance-Swap Dispersion trade at a HIGHER fair correlation strike than an OTC Clean Correlation Swap?
Wait—check the sign! In Variance Dispersion, index variance ≈ ρ · σ̄2. Because pairwise correlation ρ spikes precisely when market volatility σ̄2 spikes (Cov(ρ, σ̄2) > 0!), E[ρ · σ̄2] = E[ρ]·E[σ̄2] + Cov(ρ, σ̄2) > E[ρ]·E[σ̄2]! Dividing E[σ_I2] by E[σ̄2] yields Variance-Weighted Implied Correlation ρ_var = E[ρ] + Cov(ρ, σ̄2)/E[σ̄2], which sits +3 to +6 points ABOVE the pure Clean Correlation Swap strike E[ρ]!
Can a dealer perfectly replicate an OTC Clean Correlation Swap statically using vanilla options?
No! Unlike an index variance swap (which replicates statically via a 1/K2 log-contract option strip), no static portfolio of vanilla index and single-stock options replicates ρ_real = [∑_{i≠j} w_i w_j ρ_ij] / [∑_{i≠j} w_i w_j] independently of σ̄2! Dealers price Clean Correlation Swaps dynamically using Stochastic Local Correlation (SLC) models and charge a convexity reserve.
How do listed-options pods fix the strike-drift problem of Dirty Straddle Dispersion without trading OTC swaps?
Either trade 3-to-5 strike "Mini Variance Strips" (20d Put, 35d Put, 50d Straddle, 35d Call, 20d Call weighted by 1/K2) on liquid constituents, OR apply a disciplined "Re-Strike Rule" rolling any single-stock straddle whose underlying spot drifts more than ±1.25 standard deviations away from strike!
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). OTC Clean Correlation Swaps vs Option-Strip "Dirty" Dispersion Mechanics. VolSurface Desk. https://volsurfacedesk.com/desk-notes/otc-correlation-swaps-vs-option-strip-dirty-dispersionRelated Index Dispersion Correlation Desk & Institutional Briefings
Explore Index Dispersion Correlation Desk Hub (20) →Index Dispersion Correlation Desk
Implied Correlation, Index Dispersion Baskets & Earnings Vol Crush: Desk ManualIndex Dispersion Correlation Desk
Two-Tier Sector Dispersion: SPX vs Sector ETFs (XLK, XLF, XLE, XLV) vs StocksIndex Dispersion Correlation Desk
Post-Earnings Volatility Crush & PEAD Calendar / Diagonal Option SpreadsIndex Dispersion Correlation Desk
Equity Repo & Hard-to-Borrow Short-Fee Spikes in Single-Stock DispersionIndex Dispersion Correlation Desk
Nasdaq-100 (NDX / VXN) Tech & Semiconductor Dispersion vs S&P 500Index Dispersion Correlation Desk
Worst-of Basket Autocallable Notes: Structured-Product Correlation SupplyIndex Dispersion Correlation Desk
Ex-Dividend American Call Early-Exercise Traps in Equity DispersionIndex Dispersion Correlation Desk
Cross-Index Dispersion Arbitrage: S&P 500 (SPX) vs Russell 2000 & EURO STOXX 50Market Insights
Traders bet on a pop for Anthropic's historic IPOMarket Insights
A massive trade in Nvidia just went off – here are the detailsRegulatory Compliance
CFTC warns Kalshi of imminent charges over notification of contracts: PoliticoMarket Insights
Crypto Liquidations Top $1 Billion as Bitcoin Tests 11-Week Low
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.