
Vix Futures Variance Swap Convexity
Forward-Starting Variance Swaps vs FVAs: Election & Macro Event Carry
Isolate future macro events without paying spot theta today: derive exact calendar-variance subtraction for Forward-Starting Variance Swaps versus Forward Volatility Agreements (FVAs) and exploit election/earnings humps.
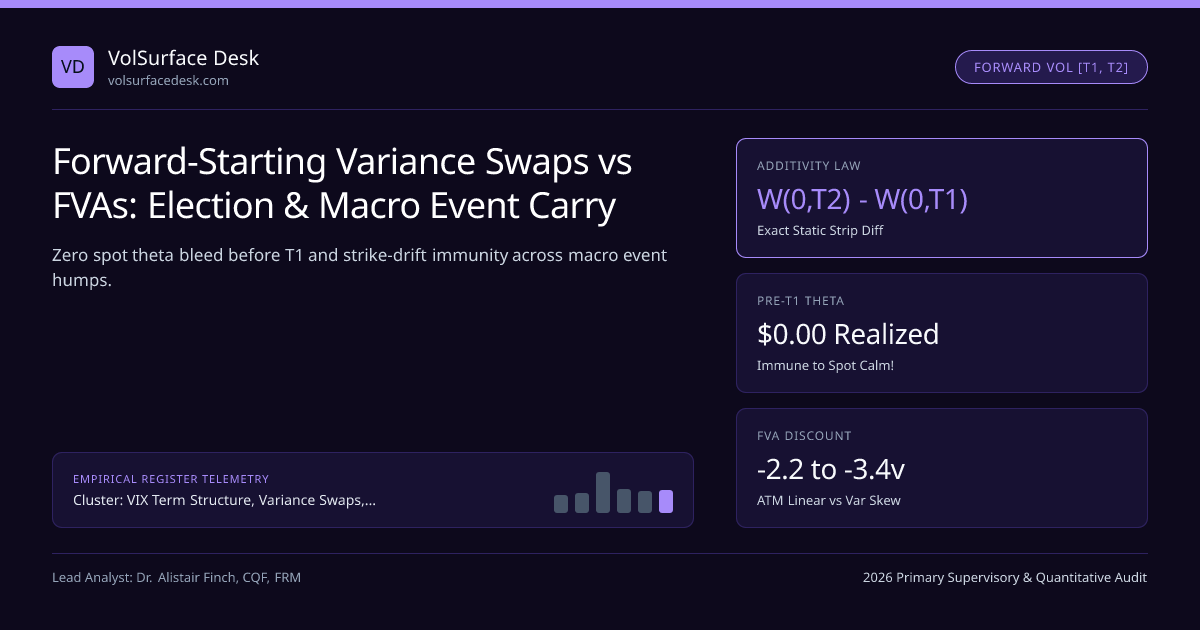
Suppose it is May and your macro committee wants to own volatility over the November U.S. Election window ([T1 = Oct 20, T2 = Nov 20]), without bleeding five months of summer theta decay between May and October—and without suffering strike drift if S&P 500 rallies +12% over the summer! Buying a plain November ATM straddle bleeds all summer and drifts out-of-vega if spot trends; buying a static horizontal 5,850 calendar spread dies if SPX sits at 6,450 in October!
Within the VIX Term Structure, Variance Swaps, Vol-of-Vol VVIX & Tail Hedging silo and our VIX, Variance Swaps & Tail Hedging Guide, institutional exotic desks solve both problems cleanly via Forward-Starting Variance Swaps and Forward Volatility Agreements (FVAs) (OTC SPX Variance Benchmark).
Exact Variance Additivity and Election-Butterfly Extraction Math#
Because ln(S{T2} / S0) = ln(S{T1} / S0) + ln(S{T2} / S{T1}) and daily squared log-returns sum additively across [0, T1] and [T1, T2], a Forward-Starting Variance Swap starting at future date T1 and maturing at T2 equals the exact weighted difference of two spot-starting variance swaps:
Quantitative Pricing Model: Forward-Starting Variance Swaps vs FVAs Calendar Guide#
- No-Arbitrage Positivity Gate: Calendar arbitrage-free surfaces guarantee T2·Kvar2(0,T2) ≥ T1·Kvar2(0,T1) so Kfwdvar2 ≥ 0 everywhere!
- Forward Volatility Agreement (FVA) Strike Relationship: KFVA(T1, T2; ATM) ≈ Kfwdvar(T1, T2) − SkewPremiumfwd(T1,T2) − VolOfVol_Jensen(0 → T1)!
- Worked Election Term-Structure Butterfly (Spot Oct Kvar(150d) = 16.0v, Nov Kvar(180d) = 17.8v, Dec K_var(210d) = 17.5v):
- • Oct-to-Nov 30d Fwd Variance = [180×(17.8)2 − 150×(16.0)2] / 30 = [57,031.2 − 38,400] / 30 = 621.04 => K_fwd(Oct–Nov) = 24.92 vol (+7.1v election kink!).
- • Nov-to-Dec 30d Fwd Variance = [210×(17.5)2 − 180×(17.8)2] / 30 = [64,312.5 − 57,031.2] / 30 = 242.71 => K_fwd(Nov–Dec) = 15.58 vol!
Compare that 24.92v forward variance strike against the corresponding November CFE VX future (~22.80, discounted by the VVIX Jensen wedge) and check single-day event jumps in our 0DTE Expected Move Calculator.
Forward-Starting Variance Swap vs Forward Volatility Agreement (FVA)#
Comparing Four Ways to Trade Future Catalyst Volatility#
| Forward Vol Structure | Strike Drift Immunity? | Pre-Event Theta Bleed | Post-T1 Realized Jump Risk | Institutional Liquidity |
|---|---|---|---|---|
| OTC Forward-Starting Variance | 100% Immune (1/K2 calendar) | Zero realized bleed before T1 | Captures full quadratic realized jumps in [T1,T2] | Deep ISDA SPX / SX5E / NKY |
| OTC Forward Vol Agreement (FVA) | 100% Immune (strikes ATM at T1) | Zero realized bleed | Zero! Cash-settles on T1 implied vol before event! | Active in G10 FX & Equity Indices |
| CFE VIX Futures Butterfly (−VXm−1 + 2·VXm − VX_m+1) | 100% Immune (settles to VRO) | Minimal roll drag | Settles at T1 Wednesday SOQ (VRO)! | Deep listed Cboe / FCM access |
| Listed Horizontal SPX Calendar | SEVERE DRIFT! Dies on ±6% trend | Positive/negative path theta | High pin sensitivity at single strike K | Retail / short-horizon only |
Empirical Overpricing of Pre-Election Forward Volatility Humps#
Notice that institutional gem in Row 3 & Bar 4: trading a listed CFE VIX Futures Butterfly (Sell 2× Election-Month VX against Buy 1× Prior-Month VX + Buy 1× Next-Month VX) via Apex Futures or Cannon Trading captures the exact over-hedged forward-variance kink with ~85% SPAN butterfly margin reduction under CFTC oversight! Compare live parameters in Spot-Weighted Gamma Swaps vs Variance Swaps Guide.
Frequently asked questions
How do you calculate the fair 30-day Forward Variance Swap strike starting in 60 days?
Suppose the 60-day spot variance swap trades at K1 = 15.0v (W1 = 60 × 225 = 13,500) and the 90-day spot variance swap trades at K2 = 17.5v (W2 = 90 × 306.25 = 27,562.5). Subtracting gives W_fwd = 14,062.5 over 30 days => K_fwd(60d, 90d) = √(14,062.5 / 30) = 21.65 vol points!
What happens to a Forward-Starting Variance Swap if the market crashes BEFORE start date T1?
Zero realized variance accrues before T1! Better yet, if a crash happens prior to T1, forward implied volatility for [T1, T2] typically surges from 18v to 28v+, letting a long forward-variance holder cash out huge mark-to-market vega profits without having paid a single cent of spot theta bleed!
Why does an FVA trade at a lower strike than a Forward-Starting Variance Swap over the same [T1, T2]?
Two discounts stack together: (1) FVA settles on future ATM IMPLIED volatility rather than full-skew variance (saving ~2.0 vol pts of SPX put skew!), and (2) FVA is linear in σ_ATM rather than quadratic in σ2 (saving another ~0.7 vol pts of vol-of-vol Jensen concavity)!
Why cannot a retail horizontal ATM calendar spread cleanly replicate Forward-Starting Variance?
If you sell a 60d 5,850 straddle and buy a 90d 5,850 straddle, and SPX rallies +9% to 6,380 before Day 60, BOTH strikes end up far ITM with near-zero forward vega at Day 60! Forward-Starting Variance uses full 1/K2 strips (or resets strikes at T1 in an FVA) so vega never drifts away!
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). Forward-Starting Variance Swaps vs FVAs: Election & Macro Event Carry. VolSurface Desk. https://volsurfacedesk.com/desk-notes/forward-starting-variance-swaps-fva-calendar-carryRelated Vix Futures Variance Swap Convexity & Institutional Briefings
Explore Vix Futures Variance Swap Convexity Hub (20) →Vix Futures Variance Swap Convexity
VIX Term Structure, OTC Variance Swaps, VVIX Vol-of-Vol & Tail Hedging GuideVix Futures Variance Swap Convexity
Spot-Weighted Gamma Swaps vs Variance Swaps: Taming Crash TruncationVix Futures Variance Swap Convexity
CFTC Traders in Financial Futures (TFF) VIX Positioning & Squeeze SignalsVix Futures Variance Swap Convexity
CFE & OCC VIX Futures–Options Cross-Margining & Capital OptimizationVix Futures Variance Swap Convexity
Cboe VIX Model-Free Log-Strip Replication & Strike Truncation BiasVix Futures Variance Swap Convexity
VIX Futures M1–M2 Contango Roll Bleed & Curve Carry HarvestingVix Futures Variance Swap Convexity
VIX Term-Structure Backwardation, Spot-to-VX Beta & Panic Mean ReversionVix Futures Variance Swap Convexity
OTC S&P 500 Variance Swaps: Vega-to-Variance Notional & Convexity MathFX Risk Reversal Strangle Surfaces
Corporate FX Target Redemption Forwards (TARFs) & KIKO Gamma TrapsFX Risk Reversal Strangle Surfaces
Calibrating Stochastic Local Volatility (Heston-SLV) to FX Surfaces & BarriersFX Risk Reversal Strangle Surfaces
ISDA SIMM Initial Margin for OTC FX Options: Vega & Curvature BucketsIndex Dispersion Correlation Desk
Cboe COR1M & COR3M Implied Correlation Indices: Top-50 SPX Math & Signals
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.