
De-Americanizing Single-Stock Equity Options Under Discrete Cash Dividends
Listed US single-stock equity options are American-style with discrete cash dividends, requiring binomial/PDE early-exercise stripping before European SVI fitting.
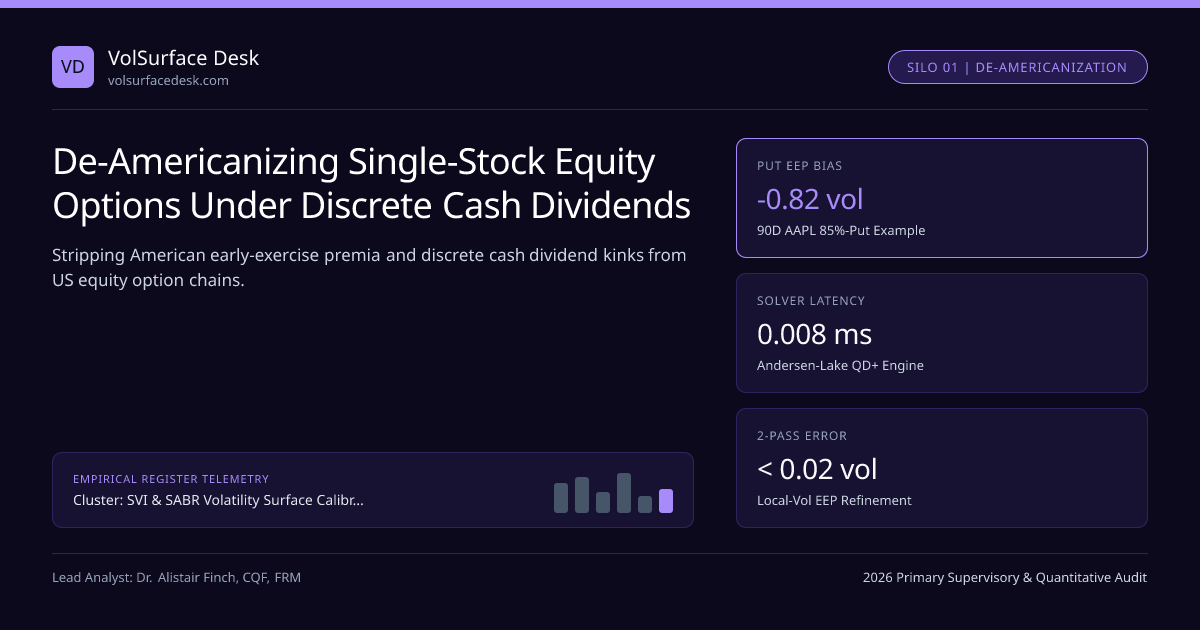
Every listed single-stock equity option and ETF option cleared by OCC on Cboe, Nasdaq PHLX, and NYSE Arca trades with American early-exercise rights and discrete quarterly cash dividends—not proportional continuous dividend yields! Plugging raw American market prices into a European Black-Scholes formula inflates deep in-the-money put implied volatilities by 0.60 to 3.40 vol points (when short-term SOFR sits at 4.25%) and distorts call implied volatilities just ahead of ex-dividend dates. Inside our SVI & SABR Volatility Surface Calibration & No-Arbitrage Conditions architecture, de-Americanization converts observed American bid/ask quotes into clean synthetic European implied volatilities prior to Gatheral raw SVI or SSVI optimization.
Escrowed vs Piecewise-Lognormal ( Buehler ) Dividend Models#
How you model a discrete $1.25 quarterly cash dividend paid at ex-date t_d changes option valuation and calendar arbitrage properties dramatically:
- Naive Escrowed Dividend Model: Splits St = S*t + PV(Divs) where S*t is geometric Brownian motion. While fast, it implies zero volatility on the dividend cash component prior to td, underpricing volatility before ex-dates and mis-locating early call exercise boundaries.
- Piecewise-Lognormal / Affine Cash-Proportional Hybrid (Buehler 2010): Decomposes St = Ft · Xt + Dcash(t) with smooth ex-date jump ΔS = −(αdiv + βdiv · S{td−}), preventing negative stock prices in crash scenarios while keeping pure martingale Xt (with E[Xt] = 1) completely free of ex-date calendar kinks!
Single-Stock Option De-Americanization & Dividend Stripping Pipeline#
Exact Early-Exercise Premium (EEP) Stripping Math#
Let VAmer^mkt(K, T) denote the observed market mid-price of an out-of-the-money or near-the-money American put or call. Standard industry de-Americanization proceeds by finding the constant volatility σ̂(K, T) under which an American solver (such as a 251-step Leisen-Reimer binomial tree with discrete dividend jumps, or Andersen, Lake, and Offengenden's 2016 Chebyshev quadrature integral solver running in 8 microseconds!) matches VAmer^mkt(K, T), and then mapping that volatility onto the clean European Black-76 contract:
- Early-Exercise Triggers: Calls exercise solely at td− if Dj > K·[1 − exp(−r·(T − td))] + PutEuro(S − Dj, K, T − td); Puts exercise continuously when r·K > qborrow·S + ΘEuro.
- Worked AAPL 90-DTE 85%-Moneyness Put (S0 = $230.00, K = $195.00, T = 0.2466 yr, SOFR r = 4.35%, D = $0.26 at t_d = 0.11 yr):
- Market American Put Price = $2.48; Naive European Black-Scholes IV inversion gives σ_naive = 28.94% (artificially inflated!).
- Andersen-Lake De-Americanized Inversion: Early-Exercise Premium EEP = $0.14 => VEuro^clean = $2.34, True Volatility σclean = 28.12% (−0.82 vol bias removed!).
Once de-Americanized, traders verify European Black-Scholes sensitivities directly in our Black-Scholes Option Calculator and Implied Volatility Calculator.
Iterative Local-Volatility De-Americanization Correction#
Wait: does de-Americanizing each strike K with a flat tree volatility σ_clean(K) introduce a subtle smile-dependent second-order error? Yes! On high-skew technology or biotech stocks where ATM vol is 45% and 80%-put vol is 68%, an American put exercising along a downward path experiences local volatility variations along the exercise boundary S(t). Tier-1 equity market makers run two fixed-point iterations*:
- Pass 1: Strip flat-tree EEP(K) and fit an initial SSVI surface.
- Pass 2: Recompute EEPLV(K) on a 1D Dupire local-volatility PDE grid derived from Pass 1, subtract EEPLV(K) from V_Amer^mkt(K), and refit SVI—converging to < 0.02 vol precision!
| Stock Regime | Dominant Early Exercise | Naive European Error | Production De-Amer Solver | Regulatory / Clearing Link |
|---|---|---|---|---|
| Mega-Cap Low Div (r = 4.35%) | Continuous Downside Puts | +0.80 to +2.40 vol put wing | Andersen-Lake QD+ Integral | OCC STANS Margin |
| Utility / Bank High Cash Div | Discrete Ex-Date Calls | +1.45 vol call kink + cal arb | Buehler Affine + LR-251 Tree | FINRA Rule 4210 TIMS |
| Hard-to-Borrow (q_b > r) | Continuous Upside Calls | +3.80 vol call wing distortion | Borrow-coupled PDE (Repo Clean) | U.S. SEC Rules |
| European Cash Index (SPX) | Zero (European Settlement) | 0.00 vol (exact European) | Direct Raw SVI Fit | Cboe Exchange |
Clearinghouse Assignment & Margin Alignment#
Because OCC STANS intraday margin snapshots and FINRA Rule 4210 TIMS portfolio margin explicitly value American early-exercise optionality, pairing borrow-rate extraction with 2-pass de-Americanization inside SVI & SABR Volatility Surface Calibration & No-Arbitrage Conditions protects market makers from both phantom SVI wing skew and surprise ex-dividend assignment losses.
Frequently asked questions
Why do Leisen-Reimer binomial trees always use an odd number of steps (e.g., 251) during de-Americanization?
Standard Cox-Ross-Rubinstein trees oscillate in saw-tooth fashion as strikes cross lattice nodes; Leisen-Reimer (1996) uses Peizer-Pratt normal inversions with an odd step count to center the terminal lattice exactly on strike K, achieving smooth O(1/N^2) convergence.
When can an American call option be exercised early if the stock pays zero cash dividends?
Only when the stock is hard-to-borrow (q_borrow > 0)! A short-stock hedger or long-call holder forfeits borrow rebate q_borrow * S by delaying exercise; whenever q_borrow * S exceeds r * K plus remaining put optionality, optimal early call exercise triggers even with zero dividends.
Why does the naive escrowed dividend model S_t = S*_t + PV(D) underestimate implied volatility before ex-dates?
Because PV(D) has zero volatility in the escrowed model, instantaneous spot volatility equals sigma* * (S - PV(D)) / S < sigma*, artificially depressing spot variance prior to the ex-dividend date.
Are SPY ETF options European or American, and do they require de-Americanization?
Unlike cash-settled European SPX index options, SPY ETF options are physically settled American options paying quarterly cash distributions—so SPY surfaces absolutely require de-Americanization and ex-dividend stripping!
Publication record
- Published
- November 14, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). De-Americanizing Single-Stock Equity Options Under Discrete Cash Dividends. VolSurface Desk. https://volsurfacedesk.com/desk-notes/american-equity-options-de-americanization-discrete-dividendsRelated Svi Sabr Smile Arbitrage Free & Institutional Briefings
Explore Svi Sabr Smile Arbitrage Free Hub (20) →Svi Sabr Smile Arbitrage Free
SVI and SABR Volatility Surface Calibration: 2026 Institutional No-Arbitrage GuideSvi Sabr Smile Arbitrage Free
Extracting Implied Forward and Borrow Rates Before Volatility Surface FittingSvi Sabr Smile Arbitrage Free
Vega-Weighted Least Squares and Bid-Ask Penalty Splines in SVI OptimizersSvi Sabr Smile Arbitrage Free
Extended SSVI Term-Structure Rho Monotonicity Across Quarterly Listed OptionsSvi Sabr Smile Arbitrage Free
Breeden-Litzenberger Risk-Neutral Density Recovery and Pareto Wing TailsSvi Sabr Smile Arbitrage Free
Kalman Filter State-Space Updates for Intraday Arbitrage-Free Volatility GridsSvi Sabr Smile Arbitrage Free
Gatheral Raw SVI Five-Parameter Total Variance Fitting on SPX Listed OptionsSvi Sabr Smile Arbitrage Free
Natural SVI and SVI-Jump-Wings Parameter Mapping for Equity Options DesksDealer Gamma Vanna Charm Flows
Overnight CME Globex ES & Cboe GTH Gamma Hedging Gaps Into 09:30 ET OpenDealer Gamma Vanna Charm Flows
Systematic Put-Write & Call-Overwrite ETFs (PUTW, XYLD, JEPI) Gamma SupplyDealer Gamma Vanna Charm Flows
Whalley-Wilmott Discrete Gamma Hedging Bandwidths Under ES Transaction CostsDealer Gamma Vanna Charm Flows
Single-Stock Call-Skew Inversion & Dealer Short-Call Gamma Squeezes
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.