
Vix Futures Variance Swap Convexity
VIX Term-Structure Backwardation, Spot-to-VX Beta & Panic Mean Reversion
Model Cboe VIX futures during crisis backwardation (Spot VIX > VX1 > VX2): derive Ornstein-Uhlenbeck e^(−κ·T) futures beta compression and identify when inverted curves transition from cascade to mean reversion.
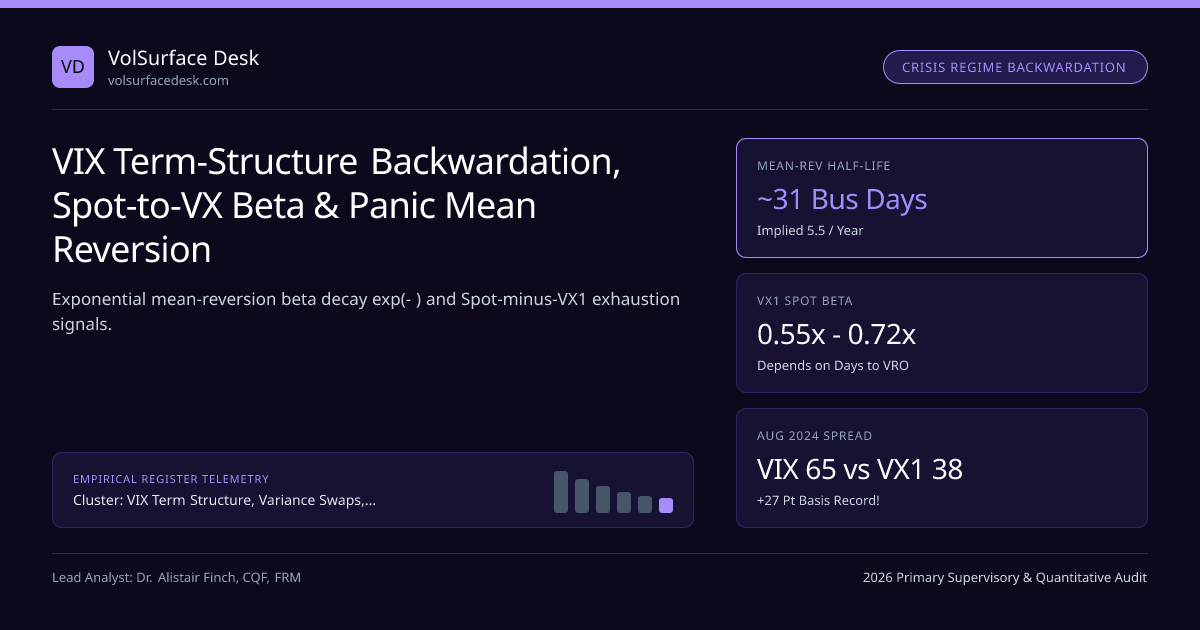
Every market crisis triggers angry headlines from retail traders whose long-volatility ETF rose only +24% on a morning when Spot Cboe VIX surged +75% from 18 to 31.5! Far from being an ETF "tracking error," that dampened response reflects the fundamental stochastic law of mean-reverting volatility futures during VX1–VX2 Backwardation Regimes.
Within the VIX Term Structure, Variance Swaps, Vol-of-Vol VVIX & Tail Hedging silo and our VIX, Variance Swaps & Tail Hedging Guide, modeling the exact exponential decay of Spot-to-VX beta across maturities (VX1 through VX6) lets institutional desks avoid overpaying for front panic while timing structural volatility normalization.
Deriving Exponential Spot-to-Futures Beta Under Heston / OU Mean Reversion#
Under the risk-neutral Heston variance diffusion dVt = κ · (θQ − Vt) dt + ξ · √Vt dWt^Q with mean-reversion rate κ > 0 and long-run risk-neutral variance θQ, expected instantaneous variance at future settlement Tm equals Et^Q[V{Tm}] = θQ + (Vt − θQ) · e^(−κ·(Tm − t)). Differentiating the m-th VIX future VX_m with respect to Spot VIX yields the term-structure beta law:
Quantitative Pricing Model: VIX Backwardation, Spot-to-VX Beta & Panic Reversion#
- Maturity Dependence: When VX1 is 2 days from Wednesday SOQ (τ1 = 0.0055 yr), β1 ≈ 0.97; when VX1 just rolled to 29 days out (τ1 = 0.079 yr, κ = 5.5), exp(−5.5 × 0.079) = 0.648!
- Backwardation Inversion Condition: VX1 > VX2 whenever Vspot > θQ + Jensen_Adjustment — typically crossing around VIX = 20.5 to 22.5!
- Worked Panic Spike Audit (Spot VIX Jumps +18.0 Pts from 16.0 to 34.0 on Day 1 of Cycle; κ = 5.5/yr, Long-Run √θ_Q = 19.5):
- VX1 (τ1 = 26d = 0.071 yr) jumps from 17.1 to 28.4 (+11.3 pts, β1 = 0.63x); VX2 (τ2 = 54d = 0.148 yr) jumps from 18.0 to 25.6 (+7.6 pts, β2 = 0.42x) => VX1 − VX2 Flips from −0.90 Contango to +2.80 Backwardation!
Traders price Black-76 VIX calls and puts directly off each maturity's forward VX_m in our Black-Scholes Option Calculator.
Lifecycle of a VIX Backwardation Regime & Normalization Trade#
Term-Structure Beta & Roll Behavior Across CFE VX Maturities#
| CFE VIX Contract Tenor | Typical Time to Settlement (τ) | Empirical Beta to Spot VIX Jump | Crisis Backwardation Role & Desk Usage |
|---|---|---|---|
| Spot Cboe VIX (Uninvestable) | 0 Days (Immediate 30d Strip) | 1.00x (Reference Benchmark) | Pure sentiment & zero-bid truncation gauge |
| Front-Month VX1 | 1 to 30 Calendar Days | 0.55x (Day 30) → 0.98x (Day 1) | Highest gamma/liquid hedge; underlies expiring front VIX options |
| Second-Month VX2 | 31 to 60 Calendar Days | 0.40x to 0.54x | Core leg of S&P Short-Term VIX ETPs (UVIX/SVIX) |
| Mid-Curve VX4 – VX6 | 90 to 180 Calendar Days | 0.20x to 0.30x | Structural recession / regime anchor; low daily roll decay |
Subsequent 20-Day Market Behavior by Spot-Minus-VX1 Basis Bucket#
Institutional macro desks executing through Cannon Trading or Daniels Trading express post-climax normalization via put spreads on front VIX options or beta-adjusted short VX1 / long VX3 spreads, strictly avoiding uncapped upside exposure in case geopolitical escalation extends Phase 2.
Frequently asked questions
Why did VX1 peak below 39 on August 5, 2024 when Spot VIX printed above 65 pre-market?
Two mechanisms combined: (1) Pre-market zero-bid truncation/wide quotes inflated Spot VIX prints at 08:35 ET, and (2) VX1 settled 11 days later—traders priced high probability that the Bank of Japan yen-carry panic would mean-revert within two weeks rather than persist for 41 days!
What is the exact formula for VIX futures sensitivity (beta) to a Spot VIX jump?
In a Heston / Ornstein-Uhlenbeck variance model dV_t = κ(θ − V_t)dt + ξ√V_t dW_t, expected future variance decays exponentially as E_t[V_{t+τ}] = θ + (V_t − θ)·exp(−κ·τ). Linearizing around √V yields ΔVX(τ) / ΔVIX_spot ≈ (VIX_spot / VX(τ)) · exp(−κ · τ) · [ (1 − e^(−κ·ΔT)) / (κ·ΔT) ]!
Is VX1 > VX2 backwardation an automatic signal to short volatility immediately?
NO! Initial entry into mild backwardation (VX1 - VX2 = +0.5 to +2.0 pts) frequently precedes the WORST phase of multi-week liquidations (such as late Feb 2020 or Sep 2008). Institutional desks wait forVVIX divergence andVX1-VX2 reversal FROM peak inversion before fading.
How does positive roll yield work for LONG VIX holders during sustained backwardation?
If Spot VIX stays elevated around 32 while VX1 = 30 and VX2 = 27.5, rolling out of expiring higher-priced VX1 into cheaper VX2 earns +8.3% POSITIVE monthly roll yield—allowing tail hedges to self-finance during prolonged bear markets like autumn 2008!
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). VIX Term-Structure Backwardation, Spot-to-VX Beta & Panic Mean Reversion. VolSurface Desk. https://volsurfacedesk.com/desk-notes/vix-futures-backwardation-spot-beta-jump-regimesRelated Vix Futures Variance Swap Convexity & Institutional Briefings
Explore Vix Futures Variance Swap Convexity Hub (20) →Vix Futures Variance Swap Convexity
VIX Term Structure, OTC Variance Swaps, VVIX Vol-of-Vol & Tail Hedging GuideVix Futures Variance Swap Convexity
OTC S&P 500 Variance Swaps: Vega-to-Variance Notional & Convexity MathVix Futures Variance Swap Convexity
Capped (2.5× Strike) vs Uncapped Variance Swaps: Left-Tail Gap RiskVix Futures Variance Swap Convexity
Corridor Variance & Conditional Down-Variance Swaps: Targeted Crash HedgesVix Futures Variance Swap Convexity
Cboe VVIX Vol-of-Vol & Jensen’s Inequality: The VIX Futures Convexity WedgeVix Futures Variance Swap Convexity
VIX 1×2 Call Ratios & Collars vs Direct SPX OTM Put Tail HedgesVix Futures Variance Swap Convexity
Ultra-Short VIX1D vs VIX9D, VIX & VIX3M Event Term-Structure KinksVix Futures Variance Swap Convexity
Wednesday Morning VIX SOQ Settlement (VRO) & SPX Strip Auction MechanicsFX Risk Reversal Strangle Surfaces
Malz Quadratic vs Vanna-Volga FX Volatility Smile InterpolationFX Risk Reversal Strangle Surfaces
FX 10-Delta Wing Butterflies vs 25-Delta Flies: Jump Kurtosis PricingFX Risk Reversal Strangle Surfaces
Overnight FX Central-Bank Event Variance Weights (FOMC, ECB, BoJ)FX Risk Reversal Strangle Surfaces
Sticky-Strike vs Sticky-Delta FX Smiles: Shadow-Delta Hedging Math
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.