
Dealer Gamma Vanna Charm Flows
FINRA Rule 4210 TIMS Portfolio Margin vs Reg T Haircuts for Index Books
Master FINRA Rule 4210(g) Theoretical Intermarket Margining System (TIMS) valuation grids (±15% equity, −8%/+10% broad index) versus Regulation T strategy rules—plus prime-broker house stress overlays.
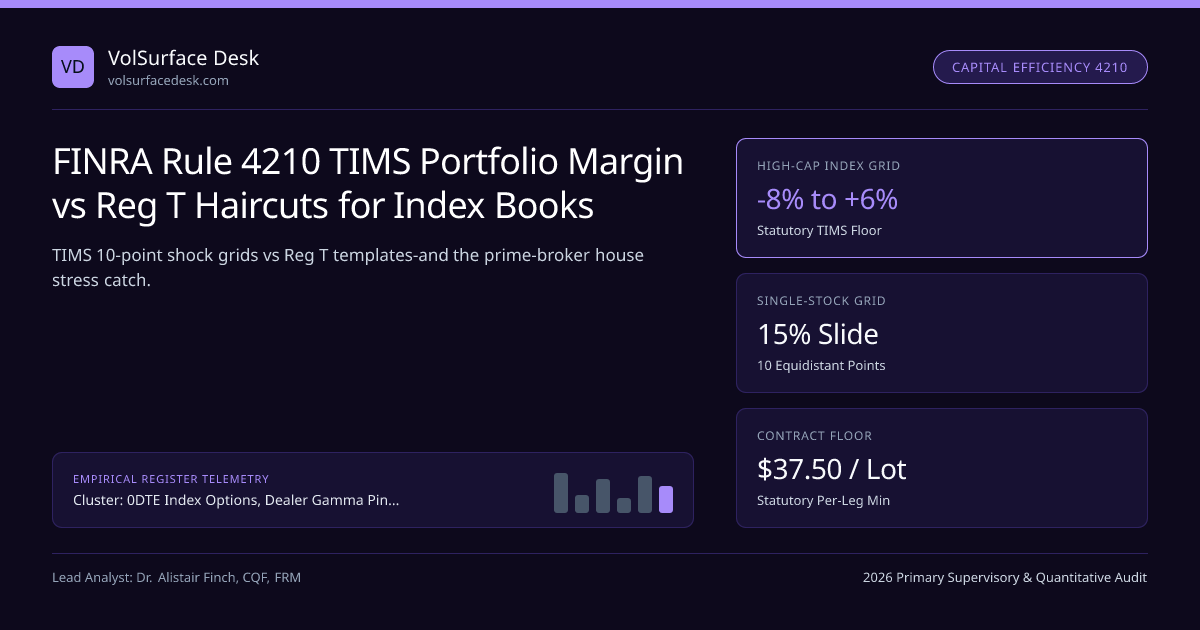
Capital efficiency determines whether an institutional volatility or dispersion strategy generates a 19% ROE or an uninvestable 4% return on cash. In U.S. securities accounts supervised by the SEC and FINRA, customer margin divides into two starkly different worlds: legacy Federal Reserve Regulation T strategy-based rules versus FINRA Rule 4210(g) Portfolio Margin powered by the OCC Theoretical Intermarket Margining System (TIMS) (FINRA Rule 4210 Portfolio Margin vs Reg T Benchmark).
Within the 0DTE Index Options, Dealer Gamma Pinning, Vanna & Charm Rehedging silo and our 0DTE Dealer Gamma, Vanna & Charm Flows Guide, mastering both TIMS math and prime-broker "house stress" overrides prevents sudden margin-call traps during volatility expansions.
Reg T Formulaic Haircuts vs TIMS 10-Point Full-Revaluation Grids#
Under Regulation T, a broker pairs options mechanically into recognized two- or four-leg templates (verticals, straddles, butterflies). Multi-asset hedges—such as hedging short Cboe SPX calls against long QQQ shares or hedging an index dispersion basket—receive zero cross-underlying credit! By contrast, FINRA Rule 4210(g) TIMS groups correlated instruments into Product Groups / Baskets and computes the worst theoretical loss across a 10-point spot valuation slide {S1, S2, ..., S_10}:
Quantitative Pricing Model: FINRA Rule 4210 TIMS Portfolio Margin vs Reg T Guide#
- Statutory Shock Ranges: High-Cap Broad Index (SPX, NDX, RUT, SPY) = [−8%, +6%]; Single-Stock Equities = [−15%, +15%]; Leveraged 3× ETFs = [−45%, +45%].
- CRITICAL FLAW of Pure Statutory TIMS: Notice σi is held CONSTANT at Sk! A short 12%-OTM SPX put spread ratio looks safest at −8% if σ_i doesn’t jump!
- Worked SPX Short 30-DTE 10-Delta Strangle Comparison (SPX = 5,850, Short 5,550 Put @ $16.50 + Short 6,060 Call @ $11.20):
- Reg T Margin = 15% × $585,000 − $30,000 OTM + $2,770 = $60,520 per strangle! Statutory TIMS (−8% slide to 5,382) = $19,480 (3.1x capital reduction!); Prime-Broker House Stress (−15% + +12v IV shock) = $34,900!
Traders run custom spot-and-volatility scenario slides on any option leg using our Black-Scholes Option Calculator and Option Greeks & GEX Calculator.
Institutional Options Margin Waterfall: Reg T → TIMS → House Stress#
Capital Efficiency Comparison Across Institutional Option Strategies#
| Option Strategy (SPX = 5,850) | Regulation T Margin | FINRA 4210 Statutory TIMS | Prime-Broker House PM | Strategic Implication |
|---|---|---|---|---|
| Delta-Hedged Long SPX Straddle + Short SPY | Charges full SPY + full straddle separately! | ~88% Cross-Offset (~$8,900) | ~$10,200 | Enables SPX-vs-SPY basis & NDX-vs-SPX switches |
| Short 1,000-Pt SPX European Box | Can lock strategy maintenance | ~$150 (4 legs × $37.50 floor) | ~$250–$500 | Institutional SOFR + 15 bps synthetic cash funding! |
| 1×4 Short 5-Delta Put Ratio | ~$178,000 (3 naked puts!) | Deceptively tiny (~$9,400!) | $68,000+ (House Tail Floor!) | Prevents Vomma short-strangle blowups |
| Index Dispersion (Short SPX / Long 50 Eq) | Prohibitive (>55% gross) | Broad vs Equity partial offset | 22%–28% Net Equity | Standard institutional dispersion wrapper |
Margin Haircut (% of Notional): Reg T vs FINRA 4210 Portfolio Margin#
One crucial operational warning: standard FINRA 4210 securities Portfolio Margin does not automatically cross-margin CME ES futures held in a separate CFTC-regulated futures account (such as Cannon Trading or Daniels Trading) unless the institution opens a unified Prime-Broker Portfolio Margin / OCC–CME Cross-Margin facility; otherwise, traders use SPY shares or SPX synthetic futures (Long Call + Short Put) inside the 4210 account to capture TIMS delta offsets.
Frequently asked questions
What are the statutory FINRA Rule 4210(g) TIMS valuation shock ranges?
Statutory regulatory minimums span -8% to +6% for high-capitalization broad-based indices (SPX, NDX, RUT), ±10% for non-high-cap broad indices, and ±15% for individual equities and narrow-based ETFs, divided into 10 equidistant valuation steps with a $37.50 per-contract minimum.
Why is statutory TIMS dangerous for ratio put spreads without prime-broker house overlays?
Suppose an account buys 1 ATM SPX put and sells 4 puts 12% out-of-the-money. Across a statutory -8% index slide with UNCHANGED implied volatility, that portfolio actually shows a theoretical PROFIT! Prime brokers therefore superimpose ±20%–30% extended slides plus +50%–100% IV surges.
How does FINRA Rule 4210 Portfolio Margin treat SPX European box spreads used for synthetic financing?
Under Reg T, borrowing cash via a short SPX box spread can tie up strategy margin. Under Portfolio Margin, a short 1,000-wide SPX European box has zero directional sensitivity across all 10 TIMS slide points, requiring virtually zero risk haircut beyond the $37.50/contract minimum!
What minimum net equity is required to qualify for FINRA Rule 4210 Portfolio Margin?
FINRA Rule 4210(g) mandates at least $100,000 minimum equity for retail customer accounts (though institutional prime brokers typically require $250,000 to $5,000,000+), real-time intraday risk monitoring capability, and approved uncovered option writing permissions.
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). FINRA Rule 4210 TIMS Portfolio Margin vs Reg T Haircuts for Index Books. VolSurface Desk. https://volsurfacedesk.com/desk-notes/finra-rule-4210-portfolio-margin-tims-vs-reg-tRelated Dealer Gamma Vanna Charm Flows & Institutional Briefings
Explore Dealer Gamma Vanna Charm Flows Hub (20) →Dealer Gamma Vanna Charm Flows
0DTE Index Options, Net Dealer Gamma (GEX), Vanna & Charm Rehedging Flows GuideDealer Gamma Vanna Charm Flows
Signed Dealer Gamma Reconstruction: Cboe Open-Close Data vs Naive OI GEXDealer Gamma Vanna Charm Flows
Monthly Third-Friday AM-Settled SPX OPEX & 09:30 ET SOQ Gamma UnwindsDealer Gamma Vanna Charm Flows
Overnight CME Globex ES & Cboe GTH Gamma Hedging Gaps Into 09:30 ET OpenDealer Gamma Vanna Charm Flows
Systematic Put-Write & Call-Overwrite ETFs (PUTW, XYLD, JEPI) Gamma SupplyDealer Gamma Vanna Charm Flows
Whalley-Wilmott Discrete Gamma Hedging Bandwidths Under ES Transaction CostsDealer Gamma Vanna Charm Flows
Single-Stock Call-Skew Inversion & Dealer Short-Call Gamma SqueezesDealer Gamma Vanna Charm Flows
0DTE Intraday Variance-Time Clock vs Wall-Clock Theta & Event JumpsVix Futures Variance Swap Convexity
Volatility Swaps vs Variance Swaps: Exact Vol-of-Vol Convexity PricingVix Futures Variance Swap Convexity
Leveraged & Inverse VIX ETPs (UVIX, SVIX): 16:00 ET TAS Rebalancing FlowsVix Futures Variance Swap Convexity
Cboe SKEW Index Above 150: Risk-Neutral Third Moment vs Crash RealityVix Futures Variance Swap Convexity
Forward-Starting Variance Swaps vs FVAs: Election & Macro Event Carry
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.