
FX Risk Reversal Strangle Surfaces
CME Listed FX Options (6E, 6J) vs Interbank OTC Smile Basis Arbitrage
Bridge the divide between centrally cleared CME listed FX options (6E Euro, 6J Yen, 6B Sterling) and bilateral interbank OTC FX surfaces: invert reciprocal quotes, align futures forwards, and capture SPAN-vs-SIMM capital savings.
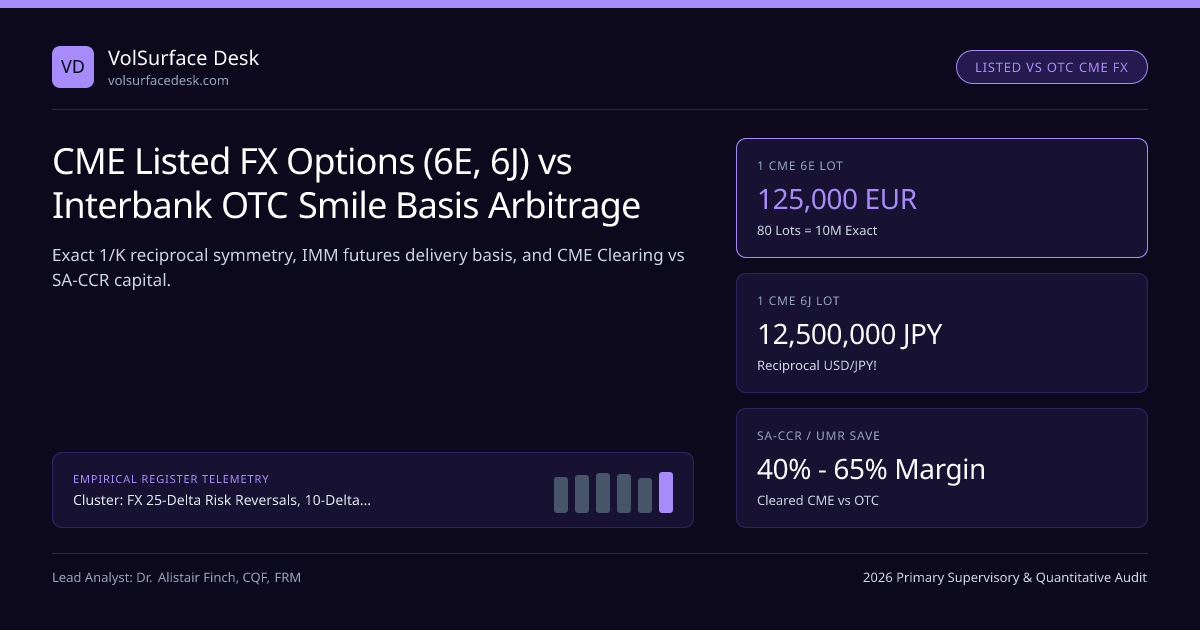
Over the past decade, Uncleared Margin Rules (UMR) and Basel III Standardized Approach for Counterparty Credit Risk (SA-CCR) made bilateral OTC FX option books substantially more capital-intensive for hedge funds and regional banks. In response, institutional FX volatility flow migrated aggressively onto centrally cleared CME Listed FX Options (6E, 6J, 6B, 6A, 6C, 6M)—creating a thriving Listed-vs-OTC FX Volatility Surface Arbitrage policed to within 0.03–0.08 vol points!
Within the FX 25-Delta Risk Reversals, 10-Delta Butterflies & Event Vol Weights silo and our FX Volatility Surfaces & Event Vol Guide, executing seamlessly across OTC ECNs and CFTC-regulated FCMs (Apex Futures, Cannon Trading, Global Futures) requires exact mastery of Reciprocal Foreign-Domestic Put-Call Duality.
Exact Reciprocal Option Duality (USD/JPY ↔ CME 6J) and IMM Forward Mapping#
In EUR/USD (6E), GBP/USD (6B), and AUD/USD (6A), CME quotes USD per 1 Foreign Unit—identical in direction to interbank OTC! However, in USD/JPY (6J), USD/CAD (6C), USD/CHF (6S), and USD/MXN (6M), OTC quotes Foreign per 1 USD (S), whereas CME quotes USD per 1 Foreign Unit (Y = 1 / S)! By Foreign-Domestic Symmetry (Put-Call Duality), an OTC USD Call / JPY Put on $NUSD notional at strike KOTC (JPY/USD) transforms without any volatility change (σCME ≡ σOTC) into a CME 6J JPY Put at reciprocal strike K6J = 1 / KOTC:
Quantitative Pricing Model: CME Listed FX Options (6E, 6J) vs OTC Smile Basis Guide#
- CRITICAL NOTIONAL SCALING: Notice the JPY notional is (NUSD × KOTC), NOT (NUSD × Sspot)! Because ¥12,500,000 is fixed per 6J contract, exact contract count equals N6J = (NUSD × K_OTC) / 12,500,000!
- Why Premium-Adjusted OTC Delta Automatically Matches Unadjusted CME 6J Delta: In CME 6J, premium is paid in USD (the QUOTE currency of JPY/USD!), so 6J naturally uses UNADJUSTED Black-76 delta—which equals OTC USD/JPY Premium-Adjusted delta automatically!
- Worked Arbitrage Conversion ($25,000,000 OTC 1M USD/JPY Call @ Strike KOTC = 155.00, FOTC = 151.80, σ = 9.65%):
- Reciprocal CME 6J Strike K_6J = 1 / 155.00 = 0.0064516 ($0.00645 / ¥ => 645.16 CME strike ticks); Exact 6J Contracts = ($25M × 155.00) / ¥12.5M = 310.00 CME 6J Puts at identical σ = 9.65%!
Traders verify Black-76 futures option premiums in our Black-Scholes Option Calculator and check quarterly IMM futures fair value in the Futures Fair Value Calculator.
CME Listed vs Interbank OTC FX Smile Arbitrage Pipeline#
Complete Reference Mapping: Interbank OTC FX vs CME Listed FX Options#
| OTC FX Pair | CME Option Root & Unit Size | Direction Match? | OTC Base Call Maps To CME... | Clearing & Margin Advantage |
|---|---|---|---|---|
| EUR/USD | 6E (€125,000 EUR) | Direct (USD/EUR) | 6E Call (80 lots = €10M) | Offsets 6E futures & cross-FX in CME SPAN 2 |
| GBP/USD | 6B (£62,500 GBP) | Direct (USD/GBP) | 6B Call (160 lots = £10M) | Tight weekly Friday & Wednesday expiries |
| USD/JPY | 6J (¥12,500,000 JPY) | INVERTED! (USD/JPY → $/¥) | 6J PUT at 1/K (N_USD·K / 12.5M lots!) | Eliminates premium-adjusted delta headaches! |
| USD/CAD | 6C (C$100,000 CAD) | INVERTED! | 6C PUT at 1/K (N_USD·K / 100k lots!) | Avoids bilateral ISDA SIMM threshold charges |
All-In Institutional Cost (Spread + Funding Drag) in Vol Points#

Look at that crisp division of labor: standard macro tenors and weekly event plays execute dramatically cheaper on CME Cleared FX Options via NFA-registered FCMs, whereas bespoke broken-date corporate cashflows and barriers belong on bilateral OTC ISDA desks!
Frequently asked questions
Is implied volatility numerically identical on USD/JPY and its reciprocal JPY/USD (CME 6J)?
YES—exact mathematical elegance! By Itô’s lemma on Y_t = 1 / S_t, d(ln Y_t) = -d(ln S_t), so instantaneous and terminal log-return variance of 1/S_t is 100% IDENTICAL to S_t! Better yet, Garman-Kohlhagen symmetry proves an S_t Call in JPY numeraire equals a Y_t Put in USD numeraire at IDENTICAL σ!
Why does an option on a March quarterly IMM 6E future differ slightly from an OTC February spot-settling FX option?
A February CME 6E option delivers a March 6E FUTURE (maturing 5 weeks later on third Wednesday of March!) rather than spot EUR/USD in February! Any stochastic volatility in the 5-week EUR-USD OIS forward-point spread between Feb expiry and Mar IMM delivery creates a tiny ~0.02–0.08v forward-point correlation basis!
How do notional sizes match between an OTC €10,000,000 EUR/USD option and CME 6E contracts?
Each standard CME Euro FX (6E) futures/option contract has an exact base notional of €125,000 EUR ($12.50 per 0.0001 pip)! Therefore, €10,000,000 OTC EUR/USD matches EXACTLY 80 CME 6E option contracts (€10,000,000 / €125,000 = 80.00)!
Why does CME listed FX option liquidity rival OTC interbank spreads during G10 macro events?
Because Uncleared Margin Rules (UMR Phases 5 & 6) and Basel SA-CCR counterparty RWA charges penalized bilateral ISDA FX options, major interbank FX dealers stream tight automated electronic volatility surfaces directly onto CME Globex central limit order books and RFQ blocks!
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). CME Listed FX Options (6E, 6J) vs Interbank OTC Smile Basis Arbitrage. VolSurface Desk. https://volsurfacedesk.com/desk-notes/cme-listed-fx-options-vs-interbank-otc-smile-basisRelated FX Risk Reversal Strangle Surfaces & Institutional Briefings
Explore FX Risk Reversal Strangle Surfaces Hub (20) →FX Risk Reversal Strangle Surfaces
FX Volatility Surfaces: 25-Delta Risk Reversals, 10d Butterflies & Event Vol GuideFX Risk Reversal Strangle Surfaces
FX Cross-Currency Volatility Triangles & Implied Correlation ArbitrageFX Risk Reversal Strangle Surfaces
Cross-Currency CIP Basis Swaps & FX Forward-Point Volatility in OptionsFX Risk Reversal Strangle Surfaces
Power Reverse Dual-Currency (PRDC) Notes & Long-Dated USD/JPY SkewFX Risk Reversal Strangle Surfaces
Garman-Kohlhagen Dual-OIS Curve Hedging: Domestic Rho & Foreign PhiFX Risk Reversal Strangle Surfaces
FX Variance Swaps vs Forward Volatility Agreements (FVAs) Desk GuideFX Risk Reversal Strangle Surfaces
Corporate FX Target Redemption Forwards (TARFs) & KIKO Gamma TrapsFX Risk Reversal Strangle Surfaces
Calibrating Stochastic Local Volatility (Heston-SLV) to FX Surfaces & BarriersIndex Dispersion Correlation Desk
Equity Repo & Hard-to-Borrow Short-Fee Spikes in Single-Stock DispersionIndex Dispersion Correlation Desk
Nasdaq-100 (NDX / VXN) Tech & Semiconductor Dispersion vs S&P 500Index Dispersion Correlation Desk
Worst-of Basket Autocallable Notes: Structured-Product Correlation SupplyIndex Dispersion Correlation Desk
Ex-Dividend American Call Early-Exercise Traps in Equity Dispersion
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.