
Index Dispersion Correlation Desk
Ex-Dividend American Call Early-Exercise Traps in Equity Dispersion
S&P 500 (SPX) index options are European cash-settled; US single-stock constituent options are American physically settled. Miss a single quarterly ex-dividend early-exercise check on an in-the-money call, and you forfeit instant cash parity!
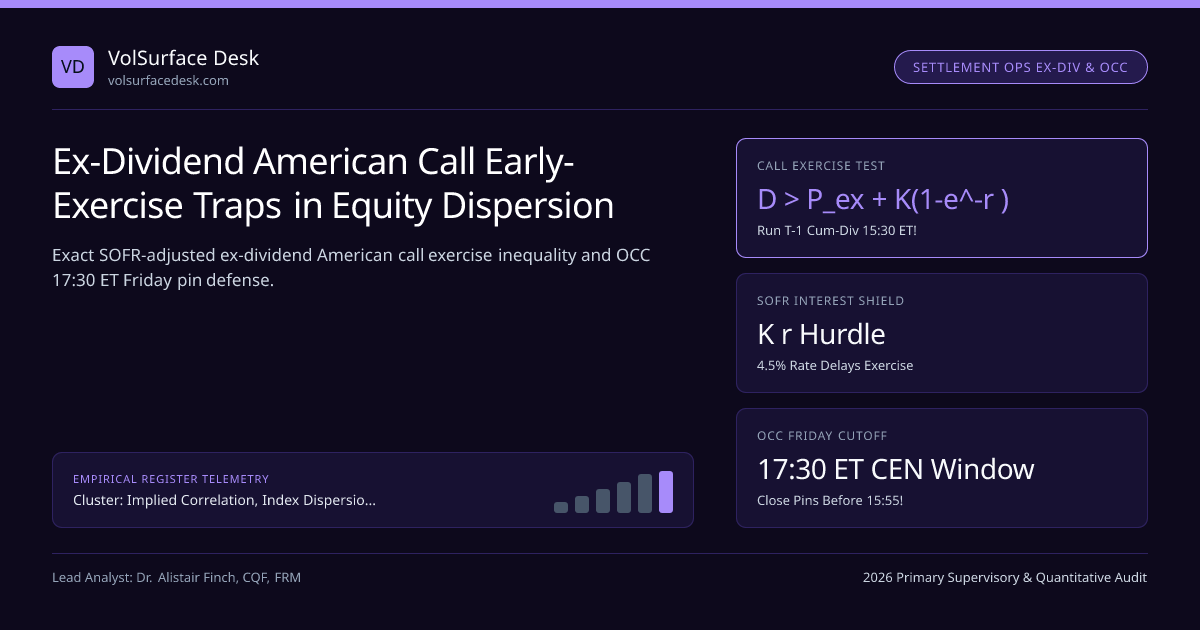
An equity index volatility quant migrating from pure European Cboe SPX and Eurex SX5E index books to cash-hedged S&P 500 Single-Stock Dispersion quickly confronts an operational minefield: SPX options are European and cash-settled, whereas all 500 US constituent equity options on OPRA are American-style and physically settled into 100 shares of stock at OCC! Neglecting Ex-Dividend American Call Exercise or Friday 17:30 ET Contrary Exercise Pin Risk silently leaks 40 to 90 bps of annualized return out of an otherwise brilliant correlation book.
Within our Implied Correlation, Index Dispersion Baskets & Earnings Vol Crush silo and Dispersion Desk Manual, every institutional desk runs automated daily Cum-Dividend Optimality Sweeps parameterized by CME SOFR.
Exact Ex-Dividend American Call Early-Exercise Inequality#
Suppose stock i trades at cum-dividend price Scum on afternoon tex− immediately prior to going ex-dividend tomorrow morning by cash dividend D, and your option expires in τ = T − tex years at SOFR OIS rate r. If you exercise your call today, your portfolio value is **Scum − K (you own the shares tonight, so tomorrow morning you hold stock worth Scum − D plus $D cash receivable = Scum!). If you do NOT exercise, tomorrow morning you hold a call on ex-dividend spot Sex = Scum − D worth, by Put-Call Parity, (Scum − D) − K · e^(−r·τ) + P(Scum − D, K, τ)**. Comparing the two proves the exact no-arbitrage exercise condition:
- Decompose the Right-Hand Side Hurdle into Two Economic Costs of Exercising Early:
- 1) Insurance Forfeiture PAmer(Sex, K, τ): Exercising converts a limited-liability Call into physical stock, giving up the matching Strike-K Put!
- 2) Cash Financing Cost K · (1 − e^(−r·τ)) ≈ K · r · τ: Paying strike cash $K today instead of τ years later forfeits SOFR interest on $K!
- Worked Comparison on Chevron (CVX, S_cum = $160.00, Quarterly Dividend D = $1.63, Strike K = $140.00, SOFR r = 4.50%):
- • At τ = 45 Days Left (Put_140 = $0.38): Hurdle = $0.38 + $140 × (1 − e^(−0.045×45/365)) = $0.38 + $0.775 = $1.155 < $1.63 ⇒ EXERCISE EARLY! (Failure to exercise loses $0.475/share = $47.50 per contract overnight!!).
- • On Microsoft (MSFT, Scum = $420, D = $0.83, K = $380, τ = 45d, Put380 = $1.20): Financing K·r·τ ALONE = $380 × 0.00553 = $2.10 > $0.83 ⇒ DO NOT EXERCISE!
Compute exact European/Black-Scholes baseline put values P(S_cum − D, K, τ) and SOFR interest carry instantly using our Black-Scholes Calculator.
Institutional Dispersion Operations: Dividend & OPEX Settlement Engine#
Operational Secret: Why Institutional Desks "Sell the Call Spread / Roll" Instead of Exercising!#
Look at Metric #2 (Better Than Exercise: Sell Call vs Stock): suppose your dispersion pod is long 200 contracts of that deep-ITM CVX $140 Call on cum-dividend afternoon (Δ ≈ 0.96, hedged against −19,200 short shares of CVX). Instead of submitting an OCC exercise instruction (which converts 200 calls into +20,000 physical shares overnight and ties up cash/balance sheet), institutional traders execute a Delta-Neutral Covered Roll on the OPRA Complex Order Book at 15:35 ET: sell the $140 Call at full cum-dividend intrinsic parity (market makers bid exact exercise parity minus $0.01!), simultaneously buy back 19,200 shares of short CVX, and re-strike into a fresh ATM $160 Straddle—capturing 99% of the dividend edge while restoring peak ATM Gamma in one atomic print!
European Index vs American Single-Stock Settlement Comparison#
| Operational Feature | S&P 500 / Nasdaq-100 Index (SPX / NDX) | US Constituent Equities & SPDR ETFs | Mandatory Desk Operational Protocol |
|---|---|---|---|
| Exercise Style | 100% European (No early exercise ever) | 100% American (Exercisable any business day) | Run daily 14:30 ET cum-div & deep-ITM put r-hurdle scan |
| Dividend Accounting | Continuous/discrete index dividend yield q_div | Discrete cash ex-dates; Call holder gets $0 div! | Check D > P_ex + K(1 − e^−rτ) on all >2.2% yield stocks! |
| Deep-ITM Put Exercise | Zero early exercise (European discount e^−rT) | Optimal to exercise early when r·K > D + Call_OTM! | Remember: in Reverse Dispersion, short deep-ITM puts get assigned! |
| Expiration Settlement | Cash Settled (AM SOQ or 16:00 PM Close) | Physical 100 Shares (17:30 ET OCC Cutoff) | Close all strikes within ±1.5% of spot by 15:45 ET Friday! |
Quarterly Call Early-Exercise Propensity by SPX Constituent Dividend Yield#
Notice Metric #2 (Deep Put Exercise on Zero-Dividend Stocks at High SOFR): when SOFR sits at 4.50%, a deep-ITM American Put on a zero-dividend tech stock WILL be exercised early so the holder receives cash $K early to earn 4.50% SOFR interest! Both sides of American exercise belong in your automated daily risk blotter. Combine this pricing model with Cross-Index Dispersion RV: SPX vs Russell 2000 & SX5E and Intraday Friday 0DTE Dispersion: Mega-Cap Gamma vs SPXW.
Frequently asked questions
What is the exact mathematical rule for exercising a long American Call the day before an ex-dividend date?
Compare the stock value + dividend if you exercise just before 16:00 ET/17:30 ET on cum-dividend day (paying strike K today and receiving cash dividend D tomorrow morning) against keeping the unexercised call (whose underlying stock drops to S_ex = S_cum − D at tomorrow’s open). By Put-Call Parity, Exercise Early iff D > Put(S_cum − D, K, τ) + K · (1 − e^(−r·τ))!
Wait—doesn’t high SOFR interest rate r = 4.5% REDUCE early call exercise compared to the zero-rate era?
YES—sharply! Look at that financing term K · (1 − e^(−r·τ)): exercising a $200 strike call 30 days early at r = 4.5% forfeits $200 × (0.045 × 30/365) = $0.74/share of cash interest! If the quarterly dividend is only $0.65/share ($1.3% yield), K·r·τ ALONE exceeds D ($0.74 > $0.65), so ZERO calls should be exercised early 30 days out! Early call exercise at r = 4.5% concentrates heavily in high-yield stocks (JPM, XOM, CVX, VZ, ABBV) or final 1–10 days before expiry!
What is "Dividend Play" market-maker arbitrage if retail or institutional holders forget to exercise ITM calls?
Because OCC assigns short call positions via random/pro-rata allocation ONLY for calls that long holders actually exercise, if 8% of ITM call holders forget to exercise on cum-dividend afternoon, options market makers holding massive offsetting long/short call spreads capture the unexercised dividend forfeiture ("breakage")!
How does Friday 17:30 ET OCC Contrary Exercise Notice (CEN) create weekend gap disasters on dispersion books?
OCC automatically exercises equity options ≥$0.01 ITM at 16:00 ET ("Exercise by Exception"), UNLESS a holder submits a Contrary Exercise Instruction by 17:30 ET based on after-hours news (e.g., an 16:20 ET FDA halt or earnings pre-announcement)! Never carry unclosed short near-the-money single-stock options past 15:55 ET on expiration Friday!
Publication record
- Published
- November 12, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). Ex-Dividend American Call Early-Exercise Traps in Equity Dispersion. VolSurface Desk. https://volsurfacedesk.com/desk-notes/ex-dividend-american-call-early-exercise-dispersion-trapsRelated Index Dispersion Correlation Desk & Institutional Briefings
Explore Index Dispersion Correlation Desk Hub (20) →Index Dispersion Correlation Desk
Implied Correlation, Index Dispersion Baskets & Earnings Vol Crush: Desk ManualIndex Dispersion Correlation Desk
Cross-Index Dispersion Arbitrage: S&P 500 (SPX) vs Russell 2000 & EURO STOXX 50Index Dispersion Correlation Desk
Intraday 0DTE & Weekly Friday Dispersion: Mega-Cap Gamma vs SPXWIndex Dispersion Correlation Desk
FINRA Rule 4210 TIMS & Prime-Broker Margin Netting on Equity DispersionIndex Dispersion Correlation Desk
M&A Merger Arbitrage Options: Pricing Bimodal Deal-Break W-Shaped SmilesIndex Dispersion Correlation Desk
Cboe COR1M & COR3M Implied Correlation Indices: Top-50 SPX Math & SignalsIndex Dispersion Correlation Desk
Vega-Neutral vs Theta-Neutral vs Variance-Neutral Dispersion Leg SizingIndex Dispersion Correlation Desk
Mega-Cap Concentration (Top-7 SPX Weights) & COR1M Compression BiasRegulatory Benchmarks
Listed Options, Futures & Volatility Derivatives Venues 2026 Licensing Benchmark: 6D Prudential Scorecard Across 72 Audited EntitiesCompliance Forensics
How to Verify Listed Options, Futures & Volatility Derivatives Venues Licences & Detect Clone Firms: 2026 Supervisory Lookup PlaybookSolvency and Protection
Investor Compensation Ceilings, Client-Money Segregation & Counterparty Risk Matrix in Listed Options, Futures & Volatility Derivatives Venues (2026)Volatility and Options
BTC & ETH Options Volatility Surface Spike and 25-Delta Put Skew Inversion During the $6.3B Exchange Exploit
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.