
FX Risk Reversal Strangle Surfaces
Garman-Kohlhagen Dual-OIS Curve Hedging: Domestic Rho & Foreign Phi
Stop ignoring interest-rate Greeks on FX options: derive exact Garman-Kohlhagen Domestic Rho (∂V/∂r_dom) and Foreign Phi (∂V/∂r_for), spot why spot-delta hedging leaves hidden forward-point exposure, and hedge cleanly with FX swaps and CME SOFR futures.
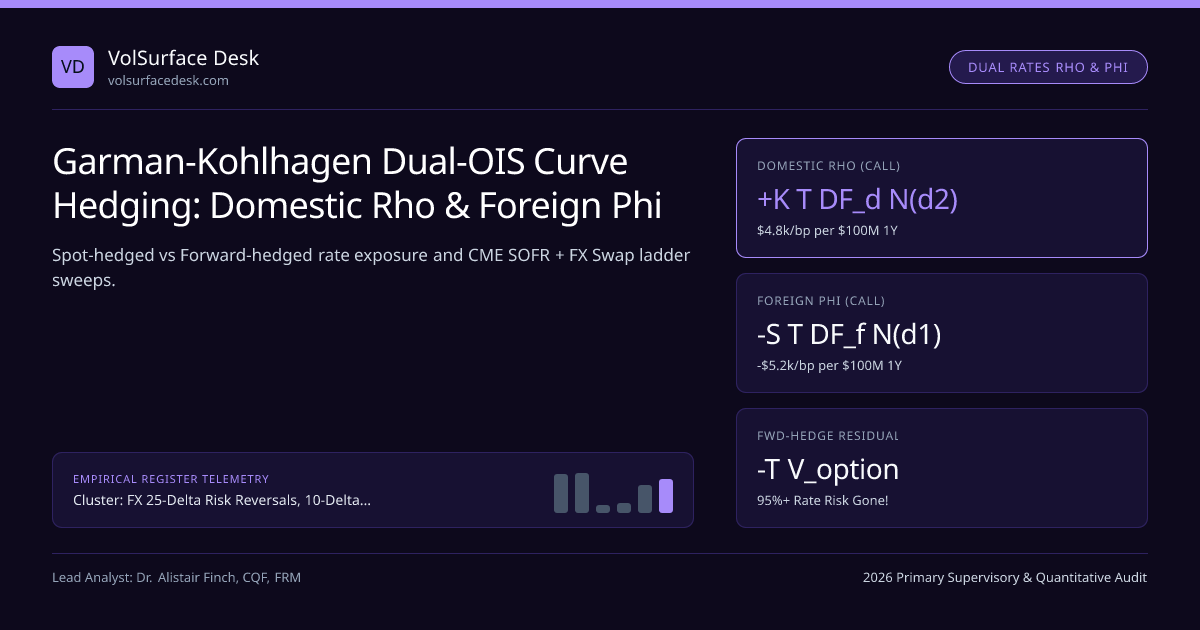
During the 2010–2021 zero-interest-rate era, sloppy options traders ignored Rho (∂V/∂r_d) and Phi (∂V/∂r_f) for an entire decade without consequence. In an active central-bank cycle where 1-year CME SOFR, ECB ESTR, and BoJ TONAR expectations swing ±25 bps in a single CPI morning, leaving dual-curve interest-rate Greeks unhedged on a 6-to-18 month FX volatility book routinely bleeds more P&L than the entire bid-ask edge of the desk!
Within the FX 25-Delta Risk Reversals, 10-Delta Butterflies & Event Vol Weights silo and our FX Volatility Surfaces & Event Vol Guide, separating Forward-Point Projection Risk from CSA Discounting Risk makes dual-curve hedging effortless.
Exact Garman-Kohlhagen Rho & Phi vs Black-76 Forward-Hedged Residual#
Write the Garman-Kohlhagen call price C = S·e^(−rf·T)·N(d1) − K·e^(−rd·T)·N(d2) alongside its exact Black-76 forward equivalent C = e^(−rd·T)·[F·N(d1) − K·N(d2)]. Differentiating before versus after locking in a T-maturity FX forward hedge −Δfwd · (F − F0) · e^(−r_d·T) proves why FX Swap Ladder Sweeps eliminate 95%+ of rate risk:
Quantitative Pricing Model: Garman-Kohlhagen Dual-OIS Curve Rho & Phi Hedging Guide#
- Forward-Hedged Greeks (Holding −e^(−r_d·T)·N(d1) Units of T-Maturity FX Forward!):
- Phifor^FwdHedged ≡ 0.00 (EXACT ZERO!) and Rhodom^FwdHedged = −T · C_option (Pure PV Discounting on Option Premium ONLY!).
- Worked €100M 1-Year EUR/USD ATM Call Comparison (S = 1.0850, rUSD = 4.30%, rEUR = 2.55%, F = 1.1042, σ = 7.40%, Call Price C = $3.28M):
- • Spot-Hedged Only: USD Rho = +$51,800/bp & EUR Phi = −$55,100/bp! A −30 bps Fed SOFR drop costs −$1,554,000 if EUR rates hold steady!
- • Forward-Hedged via 1Y EUR/USD FX Swap: EUR Phi = $0/bp & Residual USD Discounting Rho = −1.0 × $3.28M × 0.0001 = −$328/bp (−99.4% reduction—a −30 bps Fed cut moves mark by just +$9,840!).
Traders inspect exact Rho and N(d1) / N(d2) values in our Black-Scholes Option Calculator and compute forward-point differentials in the Futures Fair Value Calculator.
Institutional Spot Execution + Afternoon FX Swap & SOFR Sweep#

Comparing Rate-Hedging Protocols Across FX Option Books#
| FX Portfolio Profile | Spot-Only Delta Hedge Risk | Recommended Rate-Hedging Instrument | Execution Venue & Clearing |
|---|---|---|---|
| < 2-Week Tactical Event Book | Tiny (< $400/bp per $100M) | Roll overnight Tom-Next (T/N) FX swaps | Prime-Broker FX ECN (ATC Brokers) |
| 1M – 1Y Vanilla Surface Book | Severe ($12k–$52k/bp) on CPI/Fed days! | Matched-Tenor FX Swaps (Spot vs 3M/6M/1Y Fwd) | Interbank FX Swap / CME FX Link |
| Deep ITM / Multi-Year Collars | Large -T · V CSA discounting drift | FX Swaps PLUS CME SR3 SOFR Futures | CME / Apex Futures (CFTC) |
| Exotic RKO / PRDC | Discontinuous Rho cliff near Knock-Out! | Dynamic OIS Swap Ladder + Swaption Vega | Cleared LCH / CME IRS + OTC |
Unhedged Rate DV01 ($ per bp on $100M ATM Call): Spot vs Forward Hedge#

Notice one subtle bonus of hedging via FX Swaps: because market FX swap points natively embed both foreign OIS and the Cross-Currency CIP Basis α_CIP, rolling an FX Swap ladder automatically hedges CIP basis spread widening alongside central-bank policy moves!
Frequently asked questions
Why does delta-hedging an FX option with a matched-maturity FX Forward eliminate 95% of Rho and Phi risk?
Write Garman-Kohlhagen in Black-76 form: V = DF_dom(T) · [ F · N(d1) - K · N(d2) ]! Notice r_for enters ONLY inside F, and r_dom enters inside F PLUS outer discounting DF_dom(T)! Hedging with Δ_fwd = N(d1) units of the T-Forward neutralizes ∂V/∂F completely—leaving only -T · V discounting sensitivity on option premium!
How big is unhedged Rho/Phi loss if a trader spot-hedges a $100M 1-year EUR/USD call across a surprise 50 bps Fed cut?
On a $100M 1Y ATM EUR/USD call (N(d2) ≈ 0.48), Domestic USD Rho equals +$100M × 1.0 × 0.48 × 0.0001 = +$4,800 per basis point! A surprise -50 bps shift in 1Y USD SOFR without forward-point hedging loses -$240,000 instantaneously—wiping out 0.24 vol points of option edge!
When MUST a desk use CME SOFR futures/OIS swaps in addition to FX Forwards to hedge Rho?
Whenever an option sits DEEP in-the-money (where option mark V is 8%–15% of notional, making -T · V discounting Rho large!) OR on multi-year exotic portfolios (TARFs, PRDCs, Barrier strips) where cashflow timing is uncertain across tenors!
How do interbank FX option traders bundle FX Swap hedges efficiently across thousands of strikes?
Rather than booking a separate 87-day FX forward on every single option ticket, automated spot desks execute all intraday delta hedges in liquid Spot FX (EBS/ECNs), and once each afternoon sweep net tenor-bucketed Rho/Phi ladders using 1M, 3M, 6M, and 1Y FX Swaps + CME SOFR futures!
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). Garman-Kohlhagen Dual-OIS Curve Hedging: Domestic Rho & Foreign Phi. VolSurface Desk. https://volsurfacedesk.com/desk-notes/garman-kohlhagen-dual-ois-curve-rho-phi-fx-hedgingRelated FX Risk Reversal Strangle Surfaces & Institutional Briefings
Explore FX Risk Reversal Strangle Surfaces Hub (20) →FX Risk Reversal Strangle Surfaces
FX Volatility Surfaces: 25-Delta Risk Reversals, 10d Butterflies & Event Vol GuideFX Risk Reversal Strangle Surfaces
FX Variance Swaps vs Forward Volatility Agreements (FVAs) Desk GuideFX Risk Reversal Strangle Surfaces
Corporate FX Target Redemption Forwards (TARFs) & KIKO Gamma TrapsFX Risk Reversal Strangle Surfaces
Calibrating Stochastic Local Volatility (Heston-SLV) to FX Surfaces & BarriersFX Risk Reversal Strangle Surfaces
ISDA SIMM Initial Margin for OTC FX Options: Vega & Curvature BucketsFX Risk Reversal Strangle Surfaces
FX ATM Delta-Neutral Straddles (DNS) & Premium-Adjusted Delta ConventionsFX Risk Reversal Strangle Surfaces
FX 25-Delta Risk Reversals: USD/JPY & EUR/USD Carry Crash SkewFX Risk Reversal Strangle Surfaces
FX Market Strangle (1-Vol) vs Smiley Broker Butterfly (2-Vol) IterationIndex Dispersion Correlation Desk
Cross-Index Dispersion Arbitrage: S&P 500 (SPX) vs Russell 2000 & EURO STOXX 50Index Dispersion Correlation Desk
Intraday 0DTE & Weekly Friday Dispersion: Mega-Cap Gamma vs SPXWIndex Dispersion Correlation Desk
FINRA Rule 4210 TIMS & Prime-Broker Margin Netting on Equity DispersionIndex Dispersion Correlation Desk
M&A Merger Arbitrage Options: Pricing Bimodal Deal-Break W-Shaped Smiles
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.