
Vix Futures Variance Swap Convexity
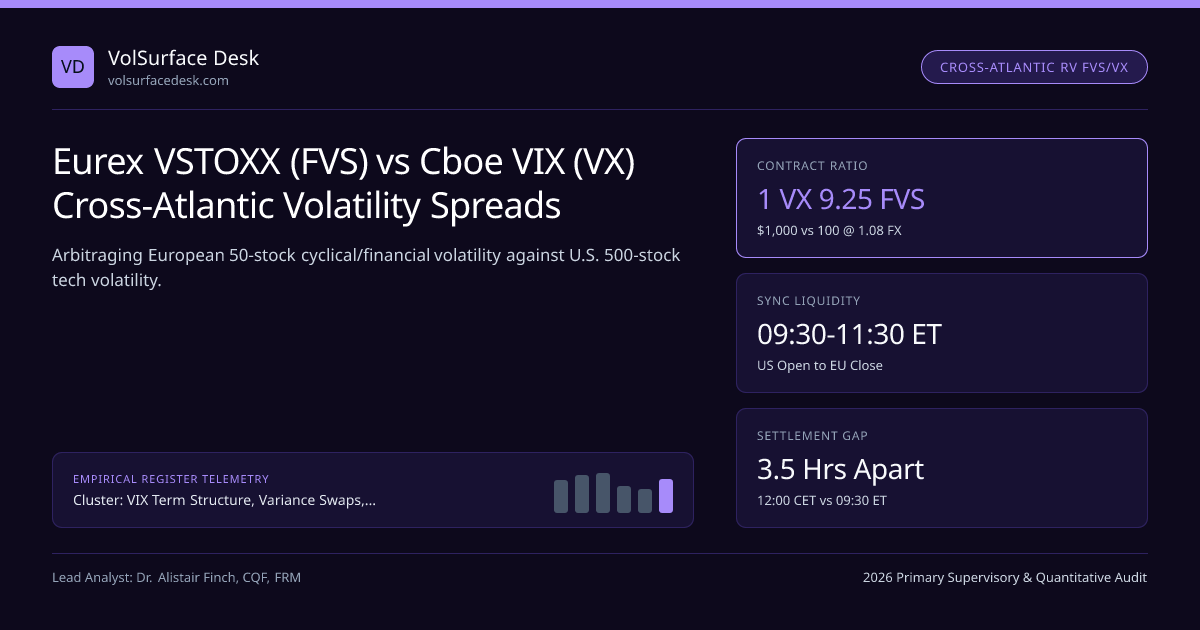
Eurex VSTOXX (FVS) vs Cboe VIX (VX) Cross-Atlantic Volatility Spreads
Structure institutional cross-Atlantic volatility spreads between Eurex VSTOXX Mini-Futures (FVS, €100/pt) and Cboe VIX Futures (VX, $1,000/pt): sector composition divergences, EUR/USD FX carry, and geopolitical mean reversion.
Global macro volatility desks never confine relative-value trading to U.S. shores. Pairing Eurex VSTOXX Futures (FVS)—the benchmark 30-day volatility contract on the EURO STOXX 50 (SX5E), supervised under BaFin and ESMA—against Cboe VIX Futures (VX) (VX1–VX2 Term-Structure Benchmark) unlocks one of the cleanest liquid mean-reverting volatility spreads in institutional derivatives.
Within the VIX Term Structure, Variance Swaps, Vol-of-Vol VVIX & Tail Hedging silo and our VIX, Variance Swaps & Tail Hedging Guide, structuring FVS − VX spreads properly requires exact calibration of FX-adjusted contract ratios, vol-beta weighting, and 50-vs-500 constituent concentration.
FX-Adjusted Notional Sizing, Quanto Correlation, and Beta Weighting#
Because Cboe VX pays $1,000 USD per index point (0.05 min tick = $50) while Eurex FVS pays €100 EUR per index point (0.05 min tick = €5), a USD-denominated fund trading NFVS Eurex contracts against NVX Cboe contracts at spot exchange rate X{EURUSD} and regression vol-beta β{FVS/VX} solves:
Quantitative Pricing Model: Eurex VSTOXX (FVS) vs Cboe VIX (VX) Spread Trading Guide#
- Quanto FX Drift Correction: Because Correl(ΔVSTOXX, ΔEURUSD) ≈ −0.42 during Eurozone stress (VSTOXX spikes when EUR falls!), long FVS suffers a modest negative quanto drag in USD terms unless variation margin is swept daily!
- Constituent Concentration Wedge: SX5E (50 stocks, ~20% Banks + Industrials) vs SPX (500 stocks, ~32% US Tech) drives cyclical regime shifts between +4.5 pts (European elections/energy) and −2.8 pts (US AI/Nasdaq selloffs)!
- Worked Cross-Atlantic RV Trade (French Election Panic Pushes FVS2 to 22.40 while Cboe VX2 Sits at 16.10 => Spread = +6.30 Pts [96th Percentile!], EUR/USD = 1.080, β = 0.96):
- Short 965 Eurex FVS2 @ 22.40 vs Long 100 Cboe VX2 @ 16.10 ($100k/pt Vega-equiv). Over 25 days spread mean-reverts to +1.90 pts => Net Capture = 4.40 pts × $100,000 = +$440,000 with 82% global crash hedge!
Desks verify EUR/USD forward carry and interest-rate differentials on variation margin in our Futures Fair Value Calculator.
Cross-Atlantic Eurex FVS vs Cboe VX Relative-Value Workflow#
Structural Contract & Methodology Comparison: Eurex VSTOXX vs Cboe VIX#
| Specification Attribute | Eurex VSTOXX (V2TX / FVS) | Cboe Volatility Index (VIX / VX) | Arbitrage & Execution Nuance |
|---|---|---|---|
| Underlying Equity Index | EURO STOXX 50 (50 Eurozone blue chips) | S&P 500 (500 U.S. large caps) | U.S. mega-cap earnings move VX much more than FVS |
| Futures Point Multiplier | €100 EUR per point (FVS) | $1,000 USD per point (VX) | Requires ~9.25:1 contract ratio via multi-currency FCMs (CornerTrader, House of Borse) |
| Wednesday Final Settlement | 12:00 CET (06:00 ET) 30-min TWAP of SX5E mid-quotes | 09:30 ET (15:30 CET) single SPX opening auction (VRO) | Never hold expiring M1 spread between 06:00 ET & 09:30 ET! |
| Wing Truncation Rule | Filters options >0.50€ dark/wide spread rules | Two consecutive $0.00 bid cutoff | Different tail sensitivity during illiquid opens |
VSTOXX-Minus-VIX Spread Behavior Across Macro Regimes (Pts)#
Notice the critical operational rule in Row 3 of the table: on expiration Wednesday, Eurex FVS1 expires at 06:00 ET, leaving your Cboe VX1 leg completely naked for 3.5 hours—including right across 08:30 ET U.S. CPI releases—until VRO settles at 09:30 ET! Institutional desks always roll FVS1/VX1 spreads into M2 at least 48 hours prior to Wednesday settlement. Compare live parameters in CME SOFR Swaption Vol & MOVE Spillover Into Equity VIX.
Frequently asked questions
Why are Eurex FVS futures quoted at €100 per index point compared to Cboe VX at $1,000 per point?
Eurex redesigned VSTOXX futures around the €100-multiplier FVS contract to maximize granular liquidity across European UCITS funds and market makers. At EUR/USD = 1.08, matching $100,000 per vol point requires 100 Cboe VX contracts against ~926 Eurex FVS contracts (adjusted by empirical beta).
Does a EUR-vs-USD VSTOXX-minus-VIX futures spread carry FX quanto risk?
Yes, slightly! Because FVS P&L settles in Euros and VX P&L settles in U.S. Dollars, if a European sovereign crisis spikes VSTOXX from 18 to 38 while EUR/USD drops -5% from 1.08 to 1.026, a USD-based fund’s €2,000/lot FVS gain loses 5% on FX translation unless dynamically FX-hedged!
Why does VSTOXX typically exhibit higher baseline implied correlation than S&P 500 VIX?
A 50-stock index has higher Herfindahl concentration (1/50 = 2% average weight) and tighter Eurozone macro coupling than a 500-stock index spanning U.S. healthcare, utilities, energy, and software—lifting SX5E index variance unless mega-cap U.S. tech earnings dominate.
Do Eurex FVS futures and Cboe VX futures expire at the exact same timestamp on Wednesdays?
Same calendar Wednesday (30 days before next month’s third Friday), but DIFFERENT hours! Eurex VSTOXX settles at 12:00 CET (06:00 ET morning) over SX5E option mid-quotes between 11:30–12:00 CET, whereas Cboe VRO settles 3.5 hours later at 09:30 ET!
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Dr. Alistair Finch, CQF, FRM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Dr. Alistair Finch, CQF, FRM. (2026, November 14). Eurex VSTOXX (FVS) vs Cboe VIX (VX) Cross-Atlantic Volatility Spreads. VolSurface Desk. https://volsurfacedesk.com/desk-notes/eurex-vstoxx-vs-cboe-vix-cross-atlantic-vol-spreadsRelated Vix Futures Variance Swap Convexity & Institutional Briefings
Explore Vix Futures Variance Swap Convexity Hub (20) →Vix Futures Variance Swap Convexity
VIX Term Structure, OTC Variance Swaps, VVIX Vol-of-Vol & Tail Hedging GuideVix Futures Variance Swap Convexity
Cross-Asset Spillover: CME SOFR Bachelier Swaption Vol & MOVE Into VIXVix Futures Variance Swap Convexity
Volatility Swaps vs Variance Swaps: Exact Vol-of-Vol Convexity PricingVix Futures Variance Swap Convexity
Leveraged & Inverse VIX ETPs (UVIX, SVIX): 16:00 ET TAS Rebalancing FlowsVix Futures Variance Swap Convexity
Cboe SKEW Index Above 150: Risk-Neutral Third Moment vs Crash RealityVix Futures Variance Swap Convexity
Forward-Starting Variance Swaps vs FVAs: Election & Macro Event CarryVix Futures Variance Swap Convexity
Spot-Weighted Gamma Swaps vs Variance Swaps: Taming Crash TruncationVix Futures Variance Swap Convexity
CFTC Traders in Financial Futures (TFF) VIX Positioning & Squeeze SignalsFX Risk Reversal Strangle Surfaces
FX Cross-Currency Volatility Triangles & Implied Correlation ArbitrageFX Risk Reversal Strangle Surfaces
Cross-Currency CIP Basis Swaps & FX Forward-Point Volatility in OptionsFX Risk Reversal Strangle Surfaces
Power Reverse Dual-Currency (PRDC) Notes & Long-Dated USD/JPY SkewFX Risk Reversal Strangle Surfaces
Garman-Kohlhagen Dual-OIS Curve Hedging: Domestic Rho & Foreign Phi
VolSurface Desk Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.